Tax Certainty · Sworn CPA Turkey · Law No. 3568 Art. 12 · Communiqué No. 49 · VAT refunds
Sworn CPA Report in Turkey: When Does a Foreign-Owned Company Need One, and Who Can Sign It?
A sworn CPA report in Turkey is a certification report signed by a sworn-in Certified Public Accountant (Yeminli Mali Müşavir, YMM). It confirms to the tax office that a tax return, a VAT refund or a specific exemption complies with the law, and the sworn CPA is personally liable for what is certified. This guide explains which reports exist, when they are mandatory and how a foreign parent should organize them.
Only a sworn CPA (YMM) can sign a certification report in Turkey. Your monthly accountant, a CPA (SMMM), cannot, and your statutory auditor’s report does not replace it. Since the 2025 tax year, many foreign-owned companies need a sworn CPA report for the first time because large exemptions and deductions on the corporate tax return must now be certified.
- Legal basis: Law No. 3568 Art. 12 and Tax Procedure Law (VUK) repeated Art. 227. The sworn CPA is jointly and severally liable for tax loss, penalties and interest arising from an inaccurate certification.
- New trigger: under General Communiqué No. 49 (Official Gazette 30 December 2025), a single listed exemption or deduction above TRY 500,000, or other lines above TRY 1,000,000 in total, requires a sworn CPA report. Reduced corporate tax on incentive investments and the minimum top-up tax have no threshold.
- VAT refunds: cash refunds above TRY 50,000 are paid against a tax inspection report, a sworn CPA report or a guarantee.
- Timing: a full certification contract must be signed in the first month of the financial year (January for calendar-year companies) to count as timely.
- Two roles, two firms: a sworn CPA may not keep your books, so bookkeeping and certification are always done by different professionals.
Key facts at a glance
| Question | Answer | Legal basis or source |
|---|---|---|
| What is a sworn CPA? | A sworn-in Certified Public Accountant (Yeminli Mali Müşavir, YMM): the senior tier of the Turkish accounting profession, authorized to certify. | Law No. 3568, Arts. 2 and 12 |
| How does a CPA become a sworn CPA? | At least ten years of professional experience, a proficiency examination, a license and an oath before a court. | Law No. 3568; TÜRMOB |
| Can a CPA (SMMM) sign a certification report? | No. Certification (tasdik) is reserved to sworn CPAs. | Law No. 3568, Art. 12 |
| Can a sworn CPA keep the company’s books? | No. Sworn CPAs may not keep books or run a bookkeeping office. | Law No. 3568, Art. 2 |
| Is full certification of the tax return mandatory? | No, it is voluntary, but it removes the need for several separate reports and matters for VAT refund limits. | Certification Regulation; General Communiqués under Law No. 3568 |
| When is a sworn CPA report mandatory? | For listed corporate and income tax exemptions and deductions above TRY 500,000 (single item) or TRY 1,000,000 (other lines in total); without threshold for reduced corporate tax and minimum top-up tax. | General Communiqué No. 49 (Official Gazette 30 December 2025) |
| From which tax year? | Returns for the 2025 tax year onward. | General Communiqué No. 49 |
| When is the report filed? | With the tax return or within two months after the filing deadline, electronically. | General Communiqué No. 49 |
| What if the report is not filed? | The exemption or deduction cannot be used and a special irregularity penalty applies. | General Communiqué No. 49; VUK |
| Who is liable if the report is wrong? | The taxpayer, and jointly and severally the sworn CPA within the limits of the certification. | Law No. 3568, Art. 12; VUK repeated Art. 227 |
What is a sworn CPA report in Turkey?
A sworn CPA report in Turkey is a certification report (tasdik raporu) issued by a sworn-in Certified Public Accountant under Law No. 3568 Art. 12. It states that a tax return, refund claim or specific tax benefit has been examined against the books and documents and complies with tax law. The tax office relies on it in place of its own examination.
English-language sources use several names for the same profession: sworn CPA, sworn-in CPA, sworn financial advisor and certified tax auditor. All of them translate Yeminli Mali Müşavir (YMM). The Turkish term for the report is YMM tasdik raporu.
The report has legal weight because of the liability attached to it. If a certified item later proves inaccurate, the sworn CPA is jointly and severally liable with the taxpayer for the resulting tax loss, penalties and interest, within the limits of what was certified. That is why the tax office accepts the report and why a sworn CPA tests counterparties, not only the client’s own ledger.
Sworn CPA vs CPA vs statutory auditor: who signs what?
In Turkey a CPA (SMMM) keeps the books and files the returns, a sworn CPA (YMM) certifies tax positions to the tax office, and a statutory auditor authorized by the Public Oversight Authority (KGK) gives an opinion on the financial statements. The three roles are separate, and none of the three documents replaces the other two.
| Feature | CPA (SMMM) | Sworn CPA (YMM) | Statutory auditor |
|---|---|---|---|
| Main function | Bookkeeping, returns, advisory | Certification of tax returns, refunds and tax benefits | Audit opinion on financial statements |
| Legal basis | Law No. 3568, Art. 2(A) | Law No. 3568, Arts. 2(B) and 12 | Turkish Commercial Code Arts. 397–406; Decree-Law No. 660 |
| May keep the books? | Yes | No | Not for audit clients |
| May sign a certification report? | No | Yes | No, unless also acting as a sworn CPA under a separate engagement |
| Report addressed to | Company and tax office (returns) | Tax office | General assembly |
| Liability for certified tax | Limited to the accuracy of returns against the books | Joint and several for certified items | Civil liability under the Commercial Code |
| Typical trigger for a foreign-owned company | Every month | VAT refund, exemptions above thresholds, incentives, import VAT report | Size thresholds or group requirement |
I am a CPA, not a sworn CPA, and that separation is the point of the system. In my practice we keep the books and prepare the working file; an independent sworn CPA examines it and signs. Foreign finance teams often expect one firm to do both. Turkish law does not allow it, and a provider who says otherwise is describing two legal entities under one brand.
Which sworn CPA reports exist in Turkey?
Foreign-owned companies meet six kinds of sworn CPA report in Turkey: the full certification report on the annual corporate tax return, the exemption and deduction certification report under Communiqué No. 49, the VAT refund certification report, the special-purpose import VAT report, tax refund reports for other taxes, and capital and equity reports for the trade registry.
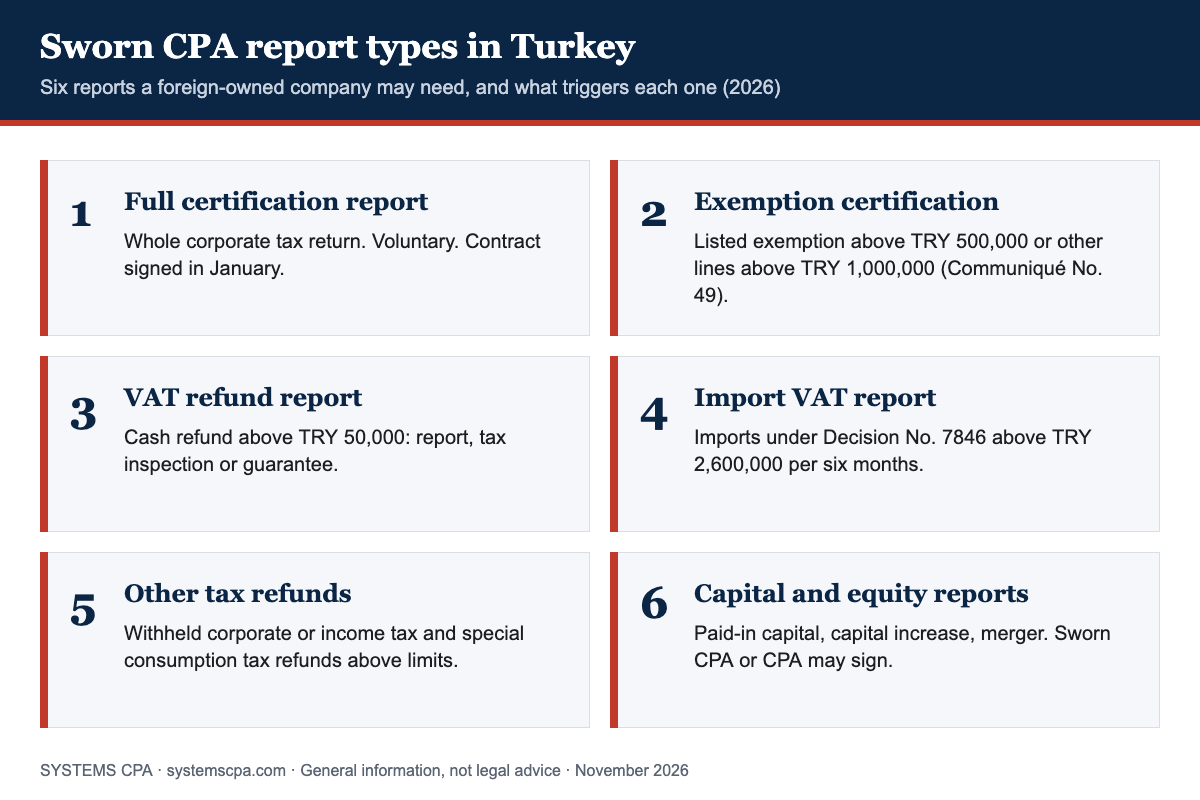
| Report | What it certifies | When a foreign-owned company needs it | Who may sign |
|---|---|---|---|
| Full certification report (tam tasdik raporu) | The annual corporate tax return and its attachments as a whole | Voluntary; chosen for VAT refund capacity, for incentives and to avoid separate reports | Sworn CPA only |
| Exemption and deduction certification report | Specific exemptions and deductions claimed on the return | Mandatory above the Communiqué No. 49 thresholds unless a full certification contract exists | Sworn CPA only |
| VAT refund certification report | That the input VAT claimed for refund was really incurred and relates to refundable transactions | Cash or offset refunds above the limits in the VAT General Implementation Communiqué | Sworn CPA only |
| Special-purpose import VAT report | That non-deductible import VAT under Presidential Decision No. 7846 was correctly excluded from deduction | Imports within scope above TRY 2,600,000 per six-month period (2026), without a timely full certification contract | Sworn CPA only |
| Other tax refund reports | Refunds of withheld income or corporate tax and special consumption tax | Refund claims above the limits set for each tax | Sworn CPA only |
| Capital and equity reports | That capital has been paid in, or the equity position before a capital increase, merger or conversion | Capital increases and restructurings filed with the trade registry | Sworn CPA or CPA (SMMM), depending on the filing |
The last row matters for search intent: many requests for a “sworn CPA report” from a foreign parent or a bank are in fact capital reports, which a CPA can also issue. Identifying the report type first avoids paying for the wrong engagement.
Does my Turkish company need a sworn CPA report?
A Turkish company needs a sworn CPA report if it claims a listed exemption or deduction above TRY 500,000 on its corporate tax return, applies reduced corporate tax under an investment incentive certificate, is subject to the minimum top-up tax, claims a VAT refund above the no-report limits, or imports goods within Presidential Decision No. 7846 above the threshold.
- Does the corporate tax return contain an exemption or deduction? Typical items for foreign-owned companies are the participation exemption on dividends, the service export deduction, technology development zone and free zone exemptions, and the R&D deduction.
- Does any single listed item exceed TRY 500,000, or do the “other” lines exceed TRY 1,000,000 in total? If yes, a sworn CPA report is required for those items.
- Does the company use reduced corporate tax under Corporate Tax Law Art. 32/A or fall under the domestic or global minimum top-up tax? If yes, certification is required regardless of amount.
- Is a VAT refund claimed in cash above TRY 50,000? The excess is paid against a tax inspection report, a sworn CPA report or a guarantee.
- Was a full certification contract signed in January? If yes, most of the separate reports above are covered by the full certification report.
If every answer is no, the company does not need a sworn CPA report this year. That is the normal position of a small sales or service subsidiary with no exemptions and no refund claims.
Communiqué No. 49: which exemptions must now be certified by a sworn CPA?
General Communiqué No. 49 under Law No. 3568, published on 30 December 2025, makes the use of listed income and corporate tax exemptions and deductions conditional on a sworn CPA certification report once thresholds are exceeded. It applies from returns for the 2025 tax year. Without the report, the exemption or deduction cannot be used and a special irregularity penalty applies.
| Item on the corporate tax return | Threshold | What must be certified |
|---|---|---|
| Any single listed exemption or deduction with its own line | Above TRY 500,000 | That item |
| “Other exemptions” and “other deductions” lines | Above TRY 1,000,000 in total | All items in those lines |
| Reduced corporate tax on incentive investments (Corporate Tax Law Art. 32/A) | No threshold | The full calculation |
| Domestic and global minimum top-up tax (Corporate Tax Law Additional Arts. 1–13 and Provisional Art. 17) | No threshold | The full calculation |
Listed items that foreign-owned companies use most often include:
- participation exemption on dividends from Turkish and foreign subsidiaries;
- the deduction for software, engineering, education and health services provided abroad (service export deduction, Corporate Tax Law Art. 10(1)(ğ));
- technology development zone (technopark) and free zone earnings exemptions;
- R&D and design deductions;
- the notional interest deduction on cash capital increases;
- share premium and investment fund exemptions.
Companies with a full certification contract do not file a separate report, provided the full certification report contains the section required by the Communiqué.
The companies caught by this rule in 2026 are not the large groups; those already had full certification. They are mid-sized foreign-owned service companies that claim the service export deduction or a participation exemption and had never spoken to a sworn CPA. My advice is to check the thresholds in the third quarter, not in April, because the sworn CPA needs to see the year as it happens.
Full certification vs special-purpose sworn CPA report: which one?
Full certification covers the whole corporate tax return under a contract signed in the first month of the year and removes the need for most separate reports. A special-purpose sworn CPA report covers one item, such as a single exemption or a VAT refund, and can be commissioned later. Companies with recurring refunds or several exemptions usually choose full certification.
| Point | Full certification | Special-purpose report |
|---|---|---|
| Scope | Entire corporate tax return and attachments | One exemption, deduction, refund or transaction |
| Contract timing | First month of the financial year to count as timely | Any time before the report deadline |
| Effect on VAT refunds | Higher refund capacity by sworn CPA report where a timely contract exists | Limited to amounts within the general limits |
| Effect on Communiqué No. 49 | No separate report if the required section is included | Separate report for each certified item |
| Work pattern | Interim reviews during the year | Concentrated after year-end or after the transaction |
| Best for | Exporters, incentive holders, groups with several exemptions | Companies with one item slightly above a threshold |
Sworn CPA report for VAT refunds in Turkey
For VAT refunds in Turkey, a sworn CPA report replaces a tax inspection for amounts above the no-report limit. As a general rule, cash refunds up to TRY 50,000 are paid without a report; the excess is paid against a tax inspection report or a sworn CPA certification report, or earlier against a guarantee that is released when the report is filed.
The sworn CPA does not only check the refund calculation. The report must confirm that the purchases behind the input VAT were real, which means reviewing suppliers and, where required, their suppliers (counter-examination). A negative finding on a supplier can block the part of the refund that relates to it.
Refund capacity by sworn CPA report also depends on a timely full certification contract. For example, in 2026 a cash refund from reduced-rate transactions above TRY 2,600,000 requires a full certification contract signed on time. The detailed refund routes are covered in our guide on how to get a VAT refund in Turkey.
How a sworn CPA report is prepared: 6 steps
- Identify the report type. Full certification, exemption certification, VAT refund, import VAT, other refund or capital report.
- Sign the certification contract. The contract between the company and the sworn CPA fixes scope, period and deliverables; full certification contracts are notified electronically by the sworn CPA.
- Prepare the working file. The company’s CPA assembles ledgers, e-invoices, contracts, bank evidence, customs declarations and calculations for the item to be certified.
- Examination. The sworn CPA tests the books and documents and carries out counter-examinations of counterparties where the rules require them.
- Draft and clear findings. Questions and corrections are resolved; returns are amended if needed before the report is finalized.
- File the report. The sworn CPA files the report electronically with the tax office within the deadline, and the company keeps the file for the statutory retention period.
Sworn CPA report deadlines
| Item | Deadline | Basis |
|---|---|---|
| Full certification contract | Within January (first month of the financial year) | Certification Regulation, Art. 10 |
| Full certification report | With the corporate tax return or within two months after it | Certification Regulation and General Communiqués |
| Communiqué No. 49 certification report | With the return or within two months after the filing deadline | General Communiqué No. 49 |
| Special-purpose import VAT report | End of the month following each six-month period (end of July and end of January) | VAT General Implementation Communiqué, as amended by Communiqué Serial No. 57 |
| VAT refund report against a guarantee | Within the period set for release of the guarantee | VAT General Implementation Communiqué |
The Revenue Administration regularly extends report deadlines by circular. Check the current year’s announcements before relying on a date.
What happens if…? Five situations
What happens if the sworn CPA report is not filed on time?
For items within Communiqué No. 49, the exemption or deduction cannot be used, so the return is treated as if the benefit had not been claimed, and a special irregularity penalty applies. For VAT refunds, the refund above the no-report limit is not paid, or the guarantee is not released, until a report or a tax inspection supports it.
What happens if no full certification contract was signed in January?
The company can still sign a certification contract later and obtain special-purpose reports. What it loses is the status of a timely contract, which affects the refund capacity available by sworn CPA report and the exemption from separate reports. For the following year, the contract should be signed in the first month.
What happens if the sworn CPA finds a problem during the examination?
The sworn CPA will not certify the item as claimed. In practice the return is corrected, the claim is reduced or the item is left out of the report. Because the sworn CPA is jointly liable for certified amounts, expect a conservative reading where documents are incomplete. Correcting before filing is cheaper than defending afterwards.
What happens if a supplier in the VAT refund file has a negative tax record?
The part of the refund linked to that supplier is normally held back until the issue is resolved or the tax office examines it. Supplier screening before purchase, not after the refund claim, is the control that prevents this.
What happens if the parent company’s auditors ask for “a sworn CPA report” on the Turkish numbers?
Clarify what they need. A sworn CPA report certifies tax matters to the Turkish tax office; it is not an audit opinion on the reporting package. If the group needs assurance on financial statements, that is a statutory or group audit engagement. See our guide to statutory audit thresholds for Turkish subsidiaries.
Case analyses: three sworn CPA report patterns
The cases below are anonymized composites built from recurring patterns. They are illustrative, do not describe any single client and do not predict the outcome of any other matter.
Case 1 — Service export deduction above the threshold
- Facts
- The Turkish subsidiary (Ltd. Şti.) of a US software group invoices engineering services to its parent and claims the service export deduction. The deduction on the 2025 return exceeded TRY 500,000. The company had never used a sworn CPA.
- The obvious answer
- File the return as in earlier years; the monthly accountant signs it.
- Why it would have failed
- Under Communiqué No. 49 the deduction now depends on a sworn CPA certification report. Without it the deduction would be denied and a penalty applied.
- The structure adopted
- The working file (contracts, invoices, proof that the service was used abroad and that the proceeds were brought to Turkey) was prepared by the company’s CPA, examined by an independent sworn CPA and the report was filed within two months of the return. A full certification contract was signed the following January.
- Lesson
- Check exemption thresholds before year-end, while documents can still be completed.
Case 2 — Exporter waiting for a VAT refund
- Facts
- A German-owned manufacturer (A.Ş.) exported most of its output and accumulated refundable VAT. It claimed cash refunds with a bank guarantee and waited for a tax inspection to release it.
- The obvious answer
- Keep renewing the guarantee.
- Why it would have failed
- Guarantee costs accumulated and working capital stayed blocked for an open-ended period.
- The structure adopted
- A full certification contract was signed in January. Monthly VAT refund certification reports released the guarantees, and supplier screening was added to purchasing so that refund files were clean before the sworn CPA saw them.
- Lesson
- For regular exporters, the sworn CPA report is a cash-flow tool, not only a compliance document.
Case 3 — The wrong report was requested
- Facts
- A foreign shareholder was told by the trade registry adviser that “a sworn CPA report” was needed for a capital increase.
- The obvious answer
- Find a sworn CPA and commission a certification engagement.
- Why it would have failed
- The document required was a report confirming that the existing capital had been paid in, which a CPA may also issue. A full sworn CPA engagement would have added time without need.
- The structure adopted
- The registry requirement was read first; the capital report was issued by the appropriate professional and the capital increase was registered on schedule.
- Lesson
- Name the report before you name the signatory.
What drives the cost of a sworn CPA report in Turkey?
The cost of a sworn CPA report in Turkey depends on the report type, the amount certified, the number of transactions and counterparties to examine, the quality of the working file, and whether the work is part of an annual full certification contract. A minimum fee tariff for sworn CPAs is published annually in the Official Gazette; actual fees are agreed in the contract.
| Driver | Lower effort | Higher effort |
|---|---|---|
| Report type | Single exemption certification | Full certification with monthly VAT refund reports |
| Amount and volume | One contract, few invoices | High refund amounts, thousands of purchase invoices |
| Counterparties | Few, well-known suppliers | Many small suppliers needing counter-examination |
| Working file | Complete, reconciled, indexed | Missing contracts, unreconciled accounts |
| Timing | Planned during the year | Commissioned days before the deadline |
| Language | Turkish report only | English summary for the parent company |
Sworn CPA in Turkey vs Germany vs the United Kingdom
The sworn CPA is a Turkish institution without a direct equivalent in Germany or the United Kingdom. In Turkey a private professional certifies tax positions to the tax office and shares liability for them. In Germany and the United Kingdom tax returns are not certified in this way; assurance comes from the statutory audit and from the tax authority’s own review.
| Point | Turkey | Germany | United Kingdom |
|---|---|---|---|
| Private certification of tax returns to the tax office | Yes, by a sworn CPA | No general equivalent | No general equivalent |
| Professional’s joint liability for the certified tax | Yes (Law No. 3568 Art. 12) | No | No |
| Separation of bookkeeping and certification | Mandatory | Not applicable | Not applicable |
| Financial statement audit | KGK-authorized auditor | Wirtschaftsprüfer | Registered statutory auditor |
The foreign-law columns are a general orientation for group finance teams, not advice on German or UK law.
How to organize sworn CPA work for a Turkish subsidiary
- List every exemption, deduction, refund and incentive the Turkish entity expects to use this year.
- Compare each one with the current thresholds in the third quarter.
- Decide between full certification and special-purpose reports before December, so that a contract can be signed in January.
- Verify the sworn CPA’s license with the chamber of sworn CPAs and confirm independence from the bookkeeper.
- Ask the bookkeeping CPA for a working-file timetable that ends well before the report deadline.
- Agree an English summary of findings for the parent company.
- Keep the certified file for the statutory retention period.
Conclusion
A sworn CPA report in Turkey is the document that lets a company use large exemptions and collect VAT refunds without waiting for a tax inspection. It can be signed only by a sworn CPA, who must be independent of the bookkeeping function. Since the 2025 tax year, more foreign-owned companies fall within the certification rules, and the decisions that matter are made in January and in the third quarter, not at the filing deadline.
Sworn CPA report readiness for Turkish entities of foreign groups
Tax Certainty before the sworn CPA opens the file. SYSTEMS CPA keeps the books, checks the certification thresholds and prepares the working file. The certification report itself is examined and signed by an independent sworn CPA (YMM), as Turkish law requires.
- Threshold check: which exemptions, deductions and refunds need a sworn CPA report this year
- Full certification vs special-purpose report recommendation
- Working file for the sworn CPA: reconciliations, contracts, e-invoice and bank evidence
- Supplier screening for VAT refund files
- Coordination with the sworn CPA and deadline tracking
- English summary of the report for the parent company and Always-on Compliance afterwards
We are licensed CPAs and do not sign certification reports. Engagements start with a paid scoping consultation, and fees are confirmed in writing.
Request the review by emailRequest a proposal
info@ozmconsultancy.com · +90 216 352 29 61 · WhatsApp +90 506 682 96 55 · Deluxia Palace, Batı Ataşehir, Istanbul
Frequently asked questions about sworn CPA reports in Turkey
What is a sworn CPA in Turkey?
A sworn CPA, or sworn-in Certified Public Accountant (Yeminli Mali Müşavir, YMM), is the senior tier of the Turkish accounting profession under Law No. 3568. A sworn CPA certifies tax returns, refunds and tax benefits to the tax office and is jointly liable for the certified amounts. A sworn CPA may not keep books.
What is the difference between a CPA (SMMM) and a sworn CPA (YMM)?
A CPA (SMMM) keeps the books, prepares financial statements and files tax returns. A sworn CPA (YMM) does not keep books; the sworn CPA examines and certifies. A sworn CPA must first have at least ten years of experience, pass a proficiency examination and take an oath.
Is a sworn CPA report mandatory for every company in Turkey?
No. A sworn CPA report is required only for specific triggers: listed exemptions and deductions above the Communiqué No. 49 thresholds, reduced corporate tax on incentive investments, minimum top-up tax, VAT and other tax refunds above the no-report limits, and certain import VAT cases. Full certification of the tax return is voluntary.
What is a full certification report (tam tasdik)?
A full certification report is a sworn CPA report covering the entire annual corporate or income tax return. It is based on a contract signed in the first month of the financial year. It is voluntary, but it replaces several separate reports and increases the VAT refund capacity available by sworn CPA report.
Can my statutory auditor issue the sworn CPA report?
Only if the person signing is a licensed sworn CPA acting under a separate certification contract. An audit opinion on financial statements is addressed to shareholders under the Turkish Commercial Code; a certification report is addressed to the tax office under Law No. 3568. They are different engagements.
Does a sworn CPA report protect the company from a tax audit?
It reduces the likelihood, because the tax office relies on the certification, but it does not remove the tax administration’s power to examine. If an examination later finds an error in a certified item, the taxpayer remains liable and the sworn CPA is jointly liable within the limits of the certification.
How long does a sworn CPA report take?
It depends on the report type and the working file. A single exemption certification with complete documents can be completed within the two-month window after the return. VAT refund reports depend on counter-examination of suppliers. Full certification runs through the year with interim reviews.
Do service exporters need a sworn CPA report for the service export deduction?
Yes, where the deduction for software, engineering, education or health services provided abroad exceeds TRY 500,000 on the return and the company has no full certification contract. Under Communiqué No. 49 the deduction then depends on a sworn CPA certification report filed within two months of the return deadline.
How much does a sworn CPA report cost in Turkey?
There is no single price. A minimum fee tariff for sworn CPAs is published each year, and the actual fee depends on report type, certified amount, transaction volume, number of counterparties and the quality of the working file. Fees are fixed in the certification contract.
Can a foreign CPA or a foreign audit firm sign a Turkish sworn CPA report?
No. Only a sworn CPA licensed in Turkey under Law No. 3568 can sign a certification report accepted by the Turkish tax office. Foreign advisers can review the file and the conclusions, but the signature must be that of a Turkish sworn CPA.
Primary sources
- Law No. 3568 on Certified Public Accountancy and Sworn-in Certified Public Accountancy, Arts. 2 and 12: mevzuat.gov.tr
- Tax Procedure Law No. 213 (VUK), repeated Art. 227: mevzuat.gov.tr
- General Communiqué No. 49 under Law No. 3568 on certification of exemptions and deductions: Official Gazette of 30 December 2025
- Corporate Tax Law No. 5520, Arts. 5, 10 and 32/A: mevzuat.gov.tr
- Value Added Tax Law No. 3065 and the VAT General Implementation Communiqué, including amending Communiqué Serial No. 57: mevzuat.gov.tr; Official Gazette of 31 January 2026, No. 33154
- Presidential Decision No. 7846 on non-deductible import VAT: Official Gazette of 24 November 2023, No. 32379
- Revenue Administration communiqués and circulars: gib.gov.tr
- Turkish Commercial Code No. 6102, Arts. 397–406: mevzuat.gov.tr
- TÜRMOB, overview of the Turkish accountancy profession: turmob.org.tr
This article is provided for general informational purposes and does not constitute legal, tax, accounting or investment advice. Thresholds, limits and deadlines change annually and are stated as of 11 November 2026. Professional advice should be obtained before taking action.
Turn Turkey compliance into certainty
SYSTEMS CPA supports foreign-owned companies with company formation, accounting, tax compliance and payroll in Turkey — one accountable local partner. Reviewed by Evren Özmen, SMMM (Certified Public Accountant), TÜRMOB Reg. No. 35675.
