Peace of Mind · Accounting takeover · Law No. 3568 · Handover within 30 days
Turkish Accountant Refuses to Hand Over Books: What Can a Foreign Owner Do?
When a Turkish accountant refuses to hand over books, the law is on the company’s side: the books and documents belong to the company, and a CPA must return them within 30 days of termination with a signed handover record. This guide explains the rules, the fee trap that usually sits behind the refusal, and six steps that get the records back.
If your accountant refuses to hand over books in Turkey, do three things in parallel: make a written demand with a deadline, settle or formally contest any unpaid fees, and secure your own access to the tax office, social security and e-document systems. Most cases end there. The chamber of CPAs and the courts are the next step if they do not.
- Ownership: statutory books and documents belong to the company, which must keep and present them.
- Duty to return: a CPA must return entrusted books and documents at the end of the engagement (Working Procedures Regulation Art. 27).
- 30 days: failing to hand them over with a handover record within 30 days of termination is a disciplinary offence.
- The fee trap: another CPA may not accept you as a client while fees to the previous CPA are unpaid (Unfair Competition Regulation Art. 7(1)(c)).
- Self-help: much of the record can be rebuilt from e-ledger copies, e-invoices, bank data and the tax office portal without the accountant.
Key facts at a glance
| Question | Answer | Basis |
|---|---|---|
| Who owns the books? | The company. It must retain them for ten years under commercial law and present them in a tax examination. | Turkish Commercial Code Art. 82; Tax Procedure Law |
| Must the accountant return them? | Yes, at the end of the engagement. | Working Procedures Regulation Art. 27 |
| By when? | Within 30 days of termination, with a handover record. | Disciplinary Regulation; Unfair Competition Regulation |
| May the accountant keep them until fees are paid? | The professional rules give no right to hold a client’s books as security for fees. | Working Procedures Regulation; professional guidance |
| Do unpaid fees matter anyway? | Yes. A new CPA may not serve a client that owes fees to another CPA. | Unfair Competition Regulation Art. 7(1)(c) |
| Where do I complain? | The chamber of CPAs where the accountant is registered. | Law No. 3568; Disciplinary Regulation |
| Can records be rebuilt without the accountant? | Largely yes, from e-ledger secondary copies, e-invoices, bank statements and tax office and social security portals. | Revenue Administration e-document rules |
Can a Turkish accountant refuse to hand over books?
No. Under the Working Procedures Regulation a Turkish CPA must keep entrusted books and documents with care and return them when the engagement ends. Under the disciplinary rules, failing to hand them over within 30 days of termination with a signed handover record is an offence. The books belong to the company, not to the accountant.
The situation is common with foreign-owned companies because the accountant often holds everything: ledgers, original invoices, payroll files, the financial seal, the passwords to the tax office and social security portals, and sometimes the company stamp. When the relationship ends badly, the foreign owner discovers that it cannot see its own records.
An accountant who refuses to hand over books usually gives one of three reasons: fees are unpaid, the year-end work is “not finished”, or nobody has asked in the right form. Each has a specific answer, set out below.
The fee trap: unpaid fees vs withheld books
Unpaid fees do not entitle a Turkish accountant to keep a company’s books, but they do stop the company from moving on: a CPA who accepts a client owing fees to another CPA commits unfair competition under the professional rules. The practical way out is to pay what is undisputed and contest the rest formally, in writing.
| Issue | Accountant | Company |
|---|---|---|
| Fees owed under the contract | May claim them and pursue collection | Should pay the undisputed part and contest the rest in writing |
| Books and documents | Must return them within 30 days of termination | May demand them regardless of a fee dispute |
| New accountant | May object if a new CPA takes the client while fees are unpaid | Needs fees settled or the dispute documented before the new CPA can accept |
| Handover record | Must prepare and sign it | Should check the list against what was entrusted |
In almost every file where an accountant refuses to hand over books, there is an unpaid invoice or an unbilled year-end fee behind it. Foreign owners often want to argue the principle first. My advice is the reverse: pay what you agree you owe, put the disputed amount in writing, and ask for the books the same day. It removes the accountant’s only practical argument and lets the new CPA accept the engagement.
Six steps when an accountant refuses to hand over books
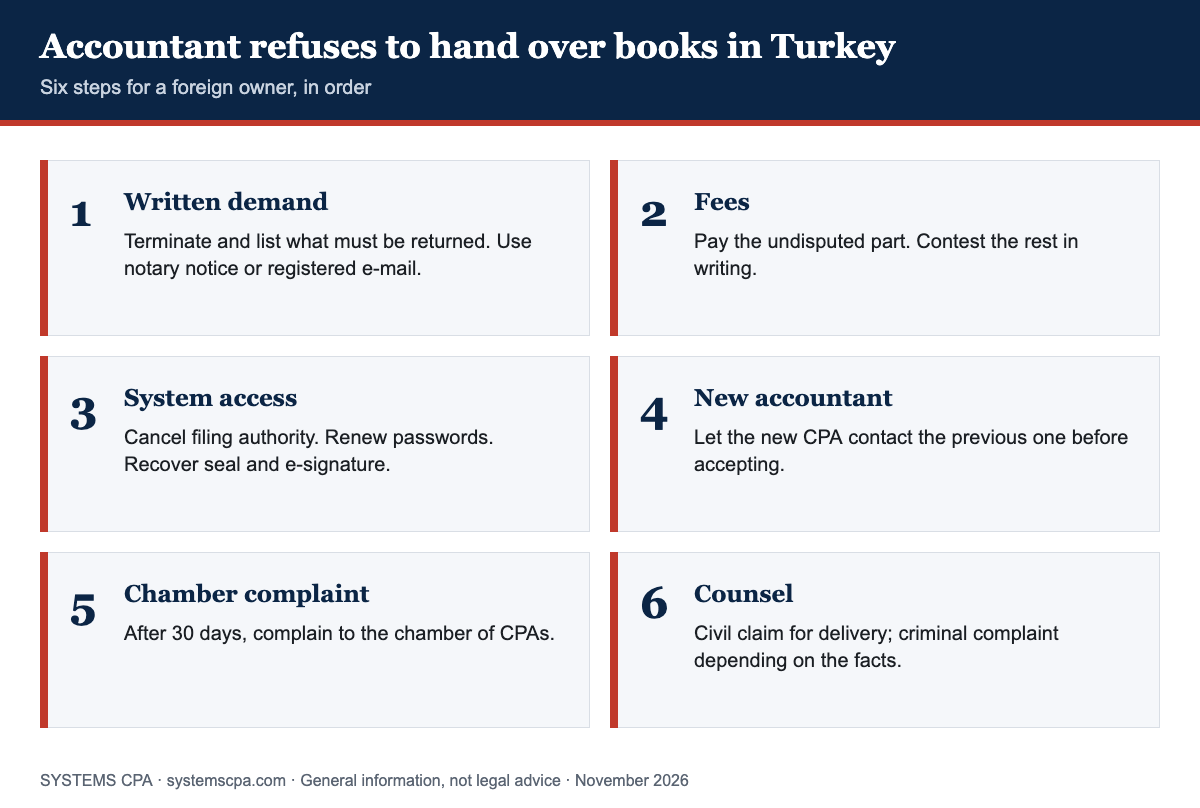
- Terminate and demand in writing. Send a dated termination and a list of what must be returned, with a deadline, by notary notice or registered electronic mail so that the 30-day period is provable.
- Deal with the fees. Pay the undisputed amount; state the disputed amount and the reason in writing.
- Take back system access. Cancel the accountant’s filing authority in the tax office system, renew the passwords for the tax office and social security portals, and recover the financial seal and e-signature devices.
- Engage the new accountant. The new CPA may contact the previous one before accepting the work; a professional-to-professional request often succeeds where the client’s did not.
- Complain to the chamber. If the 30 days pass, file a complaint with the chamber of CPAs where the accountant is registered, attaching the termination, the demand and proof of payment.
- Instruct counsel. A civil claim for delivery, interim measures and, depending on the facts, a criminal complaint are available. Whether withholding entrusted documents meets Turkish Criminal Code Art. 155 is a question for counsel.
What can you recover without the accountant?
A company whose accountant refuses to hand over books can still recover most of its record independently: e-ledger files and certificates from the secondary copies held within the Revenue Administration framework, e-invoices from the e-invoice provider, filed returns and tax accruals from the tax office portal, payroll filings from the social security system, and bank statements from the banks.
| Record | Independent source | What you need |
|---|---|---|
| E-ledger files and certificates (berat) | Secondary copies stored under Revenue Administration rules; e-ledger software provider | Company financial seal or e-signature |
| Sales and purchase e-invoices | E-invoice provider or Revenue Administration portal | Portal credentials in the company’s name |
| Filed tax returns and payment status | Digital tax office | Company’s own user code and password |
| Payroll and social security filings | Social security employer system | Employer credentials |
| Bank movements | Banks | Authorised signatory |
| Paper originals, contracts, payroll files | Only the accountant, or counterparties for copies | Handover or reconstruction |
This matters for the new accountant too. With these sources the new period can start on time, and the open question narrows to the paper originals and working papers that only the previous accountant holds.
What happens if…?
What happens if the accountant refuses to hand over books until the year-end is finished?
Finishing the year can be agreed, but it is not a condition for returning the company’s records. Agree in writing which returns the outgoing accountant will still file, and ask for copies of the books now and the originals on a fixed date.
What happens if a tax examination starts while the accountant refuses to hand over books?
The examination is addressed to the company, which is obliged to present its books. Tell the examiner in writing where the books are and what steps you have taken, and request time. Presenting e-ledger copies and e-documents obtained independently shows good faith while the originals are recovered.
What happens if the books are actually lost?
If books or documents are destroyed or lost, the Turkish Commercial Code Art. 82(7) provides for a court certificate of loss, which must be requested within the statutory period after the loss is discovered. A refusal to deliver is not a loss; do not use this route to work around a dispute.
Case analysis
Anonymized composite built from recurring patterns; illustrative only.
Case — Books held over a disputed year-end fee
- Facts
- A Dutch-owned limited company terminated its accountant in December. The accountant refused to hand over books and passwords, claiming an additional year-end fee the company had never agreed.
- The obvious answer
- Refuse to pay anything and threaten a criminal complaint.
- Why it would have failed
- The new accountant could not accept the engagement while fees were shown as unpaid, and January returns were approaching with no access.
- The structure adopted
- The company paid the contractual monthly fees, contested the extra fee in a notary notice that also demanded the books within the 30-day period, reset its portal credentials and cancelled the filing authority. The new accountant contacted the previous one; the books were delivered with a handover record before the deadline.
- Lesson
- When an accountant refuses to hand over books, separate the fee question from the records question and move on both at once.
What drives the cost when an accountant refuses to hand over books?
The cost depends on how much can be recovered from independent sources, how many periods must be reconstructed, whether the fee dispute is settled, and whether lawyers and the chamber become involved. A dispute resolved by a written demand costs little; a reconstruction of several years of paper records costs far more than the disputed fees.
| Driver | Lower effort | Higher effort |
|---|---|---|
| Records | E-ledger and e-invoice company with own credentials | Paper-heavy records held only by the accountant |
| Fees | Settled or clearly contested | Unquantified claims on both sides |
| Access | Company holds seal and passwords | Accountant holds everything |
| Route | Written demand and professional contact | Chamber complaint and litigation |
Turkey vs the United Kingdom
Both systems treat the client’s own records as the client’s property. The difference lies in enforcement tools. In Turkey there is a fixed 30-day handover period with a disciplinary sanction and a rule that blocks a new CPA while fees are unpaid. In the United Kingdom the matter is governed mainly by professional body guidance, contract and the general law on liens.
| Point | Turkey | United Kingdom |
|---|---|---|
| Deadline to return records | 30 days from termination | No single statutory period |
| Effect of unpaid fees on the new accountant | New CPA may not accept the client | Raised in professional clearance; not a statutory bar |
| Complaint body | Chamber of CPAs | The accountant’s professional body |
The UK column is a general orientation, not advice on UK rules.
Conclusion
A Turkish accountant has no right to keep a company’s books. When an accountant refuses to hand over books, a written demand, a clean position on fees and control of your own system access resolve most cases within the 30-day period, and the chamber and the courts remain available for the rest.
Accounting takeover when the previous accountant will not cooperate
Peace of Mind when you cannot see your own Turkish records.
- Inventory of what the company should hold and what is missing
- System access recovered in the company’s name
- Records rebuilt from e-ledger, e-invoice, bank and portal data
- Professional contact with the previous accountant and handover record
- New period started on time, with Always-on Compliance
We keep books and file returns as licensed CPAs; legal disputes are handled with your Turkish counsel. Engagements start with a paid scoping consultation, and fees are confirmed in writing.
Request the review by emailRequest a proposal
info@ozmconsultancy.com · +90 216 352 29 61 · WhatsApp +90 506 682 96 55 · Deluxia Palace, Batı Ataşehir, Istanbul
Frequently asked questions
Can my accountant in Turkey keep my books if I owe fees?
The professional rules do not give a CPA the right to hold a client’s books as security. Fees can be claimed separately. Unpaid fees do, however, prevent another CPA from accepting you as a client, so settle the undisputed part.
How long does a Turkish accountant have to return the books?
Thirty days from termination of the contract, with a handover record signed by both sides. Missing that period is a disciplinary offence under the rules of the profession.
Where do I complain if my accountant refuses to hand over books?
To the chamber of Certified Public Accountants where the accountant is registered. Attach the service contract, the termination notice, your written demand and proof of fee payments.
Can I get my e-ledger without my accountant?
In most cases yes. E-ledger files and their certificates are kept in secondary copies under Revenue Administration rules and by the software provider, and can be accessed with the company’s own financial seal or e-signature.
My accountant has our tax office and social security passwords. What should I do?
Renew them. The credentials belong to the company. Apply through the tax office and the social security institution with an authorised signatory, and cancel the accountant’s filing authority in the system.
Is it a crime in Turkey for an accountant to withhold company documents?
It can be, depending on the facts. Turkish legal literature discusses withholding entrusted books under the abuse of trust offence in Criminal Code Art. 155. Whether to file a complaint is a decision to take with Turkish counsel.
Primary sources
- Law No. 3568 on Certified Public Accountancy and Sworn-in Certified Public Accountancy: mevzuat.gov.tr
- Regulation on the Working Procedures and Principles of CPAs and Sworn-in CPAs, Arts. 23, 26 and 27: turmob.org.tr
- Disciplinary Regulation under Law No. 3568 (handover of books within 30 days): TÜRMOB consolidated text
- Regulation on Unfair Competition and the Advertising Ban, Art. 7: Official Gazette of 21 November 2007, No. 26707
- Tax Procedure Law No. 213, Arts. 185–186, 221 and repeated Art. 227; General Communiqué No. 340 (e-return intermediary and liability contract): mevzuat.gov.tr; gib.gov.tr
- Corporate Tax Law No. 5520, Art. 14 (filing period): mevzuat.gov.tr
- Turkish Commercial Code No. 6102, Arts. 64 and 82: mevzuat.gov.tr
- Revenue Administration e-ledger rules: edefter.gov.tr
- Turkish Criminal Code No. 5237, Art. 155: mevzuat.gov.tr
This article is provided for general informational purposes and does not constitute legal, tax, accounting or investment advice. Professional rules, deadlines and figures are stated as of 11 November 2026 and depend on the specific facts. Professional advice should be obtained before taking action.
Turn Turkey compliance into certainty
SYSTEMS CPA supports foreign-owned companies with company formation, accounting, tax compliance and payroll in Turkey — one accountable local partner. Reviewed by Evren Özmen, SMMM (Certified Public Accountant), TÜRMOB Reg. No. 35675.
