Tax Certainty · Accounting takeover · Tax Procedure Law repeated Art. 227 · Corporate tax return
Who Files the Tax Return After Switching Accountants in Turkey?
The corporate tax return after switching accountants in Turkey is filed by whichever CPA holds a valid e-return intermediary and liability contract on the filing date. Which CPA that should be is a contractual choice, and it decides who answers for last year’s numbers. This guide sets out the three workable models and what each means for liability.
When a company changes accountants at year-end, last year’s corporate tax return is still due in April. Turkish law does not say whether the outgoing or the incoming accountant files it. The law says only that the CPA who files must be authorised in the tax office system and is responsible for the return matching the books.
- Filing authority: a CPA can file only under a live e-return intermediary and liability contract (Tax Procedure Law General Communiqué No. 340).
- CPA liability: the CPA who signs is jointly liable for tax loss arising where the return does not match the books and documents (Tax Procedure Law repeated Art. 227).
- Company liability does not move: the company is the taxpayer and its legal representatives remain responsible, whoever the accountant is.
- Old periods stay with the old accountant: returns already filed remain the responsibility of the CPA who filed them, even after termination.
- Corrections: amended returns for earlier periods can be filed by the current accountant.
Key facts at a glance
| Question | Answer | Basis |
|---|---|---|
| When is the annual corporate tax return due? | 1–30 April of the following year for calendar-year companies. | Corporate Tax Law No. 5520 Art. 14 |
| Who may file it? | The CPA with a valid e-return intermediary and liability contract on the filing date. | Tax Procedure Law General Communiqué No. 340 |
| Does the law choose between old and new accountant? | No. The parties decide in their contracts. | Law No. 3568; Working Procedures Regulation |
| What is the signing CPA liable for? | Conformity of the return with the books, and of the books with the underlying documents; joint liability for resulting tax loss. | Tax Procedure Law repeated Art. 227 |
| Who is liable for tax and penalties in the first place? | The company; its legal representatives if the tax cannot be collected from it. | Tax Procedure Law Art. 10 |
| How long can an old year be reassessed? | Five years from the start of the year after the tax claim arose. | Tax Procedure Law Art. 114 |
| Can an error in an old return be corrected? | Yes, by an amended return; voluntary disclosure applies before an examination begins. | Tax Procedure Law Art. 371 |
Who files the tax return after switching accountants in Turkey?
The tax return after switching accountants in Turkey is filed by the CPA whose e-return intermediary and liability contract is valid in the tax office system when the return is submitted. Turkish law leaves the choice between the outgoing and the incoming accountant to the parties. The choice should be written into both the termination terms and the new engagement.
The question of the tax return after switching accountants arises every spring. A company changes accountants on 1 January; the financial year that ended on 31 December was kept by the outgoing firm; the annual corporate tax return for that year falls due in April. Unless someone has decided otherwise, each firm assumes the other will file.
Two rules frame the answer. First, electronic returns can be sent only by a CPA authorised under the contract recorded with the tax office. Second, the CPA who signs takes professional responsibility for the return. So filing the tax return after switching accountants is never a favour or an administrative detail; it is an assumption of liability for a year of books.
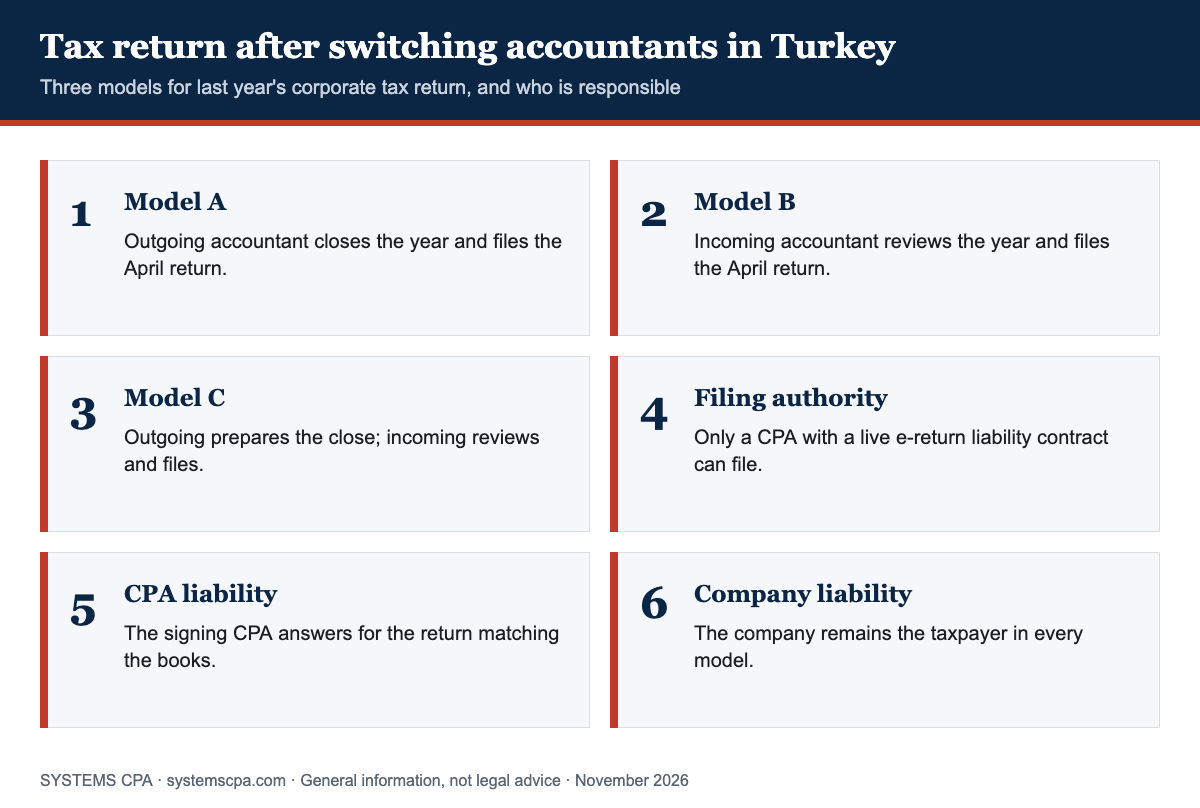
Three models for last year’s tax return after switching accountants
There are three workable models for the tax return after switching accountants: the outgoing accountant closes the year and files; the incoming accountant reviews the year and files; or the outgoing accountant prepares the close and the incoming accountant reviews and files. The right model depends on the quality of the books and on whether the outgoing accountant will cooperate.
| Model | Who closes the year | Who files in April | Works when | Main risk |
|---|---|---|---|---|
| A. Outgoing closes and files | Outgoing accountant | Outgoing accountant | The relationship is workable and the books are sound | Low motivation after termination; filing authority must remain valid for that return |
| B. Incoming reviews and files | Incoming accountant | Incoming accountant | The outgoing accountant will not cooperate or the books are in doubt | Review effort; the incoming CPA signs for a year it did not keep |
| C. Outgoing prepares, incoming files | Outgoing accountant, reviewed by incoming | Incoming accountant | Both firms cooperate under a protocol | Needs a clear cut-off and a documented review |
Under Model A, check before the old contract is cancelled in the tax office system that the outgoing accountant will still be able to submit that return. Under Models B and C, expect the incoming accountant to ask for a review of the year before signing; that is the professional duty working as intended, not an upsell.
When we are the incoming firm, I prefer Model C if the outgoing accountant is cooperative and Model B if not. I do not sign a return for a year I have not looked at, and a foreign parent should be wary of any firm that will. The review usually concentrates on bank and intercompany reconciliations, advances, payroll accruals and the tax adjustments, because that is where year-end errors sit.
Tax return after switching accountants: is the old or the new accountant liable?
The company is always the taxpayer and remains liable for tax, interest and penalties. The CPA who signed a return is jointly liable for tax loss that arises because the return did not match the books and documents. Changing accountants does not transfer the old accountant’s responsibility for returns already filed, and it does not make the new accountant responsible for them.
| Item | Outgoing accountant | Incoming accountant | Company |
|---|---|---|---|
| Returns filed before the switch | Professional responsibility remains | None | Taxpayer liability |
| Old-year annual return filed after the switch | Responsible if it files (Model A) | Responsible if it files (Models B and C) | Taxpayer liability |
| Amended returns for old periods | Not involved unless engaged | Files and signs the amendment | Decides and pays |
| Books and documents of old years | Must hand them over | Keeps them from handover | Owner; must retain and present them |
| Tax examination of an old year | May be asked to explain | Assists the company | Addressee of the examination |
Where the company has paid tax or penalties because of the outgoing accountant’s error, recovery is a contractual claim against that accountant. Whether it succeeds depends on the service contract, proof of fault and causation, and limitation periods, which is a question for Turkish counsel.
Tax return after switching accountants: what to write into the handover protocol
- Cut-off date and the trial balance at that date, signed by both firms.
- Returns list: every return due in the three months after cut-off, with the firm that files each one.
- Old-year annual return: Model A, B or C, and the date by which the closing file is delivered.
- E-ledger: who uploads the last certificates of the old year.
- Filing authority: dates on which each firm’s e-return contract starts and ends in the tax office system.
- Open items: known errors, pending corrections, open tax office correspondence.
- Fees: what is owed for closing the year, and confirmation that no fees are outstanding.
What happens if…?
What happens if the new accountant finds an error in a return the old accountant filed?
The company decides whether to correct it. An amended return for the old period can be filed by the current accountant, and voluntary disclosure under Tax Procedure Law Art. 371 is available before a tax examination or denunciation. Responsibility for the original return stays with the accountant who filed it.
What happens if neither accountant files the tax return after switching accountants?
The company bears the consequence: late-filing penalties, interest and, if the tax office assesses by estimate, a dispute about the base. This is the scenario the returns list in the handover protocol is designed to prevent.
What happens if the tax office examines a year kept by the old accountant?
The examination is addressed to the company, which must present its books and documents. The current accountant assists; the former accountant can be asked for explanations but is no longer the company’s representative. This is why the books must physically and electronically return to the company at handover.
Case analysis
Anonymized composite built from recurring patterns; illustrative only. It shows how the tax return after switching accountants goes wrong when nobody owns it.
Case — The April return nobody owned
- Facts
- A UK-owned limited company changed accountants on 1 January. In late March the parent asked for the draft corporate tax return. Each firm said the other was preparing it.
- The obvious answer
- Instruct the new accountant to file whatever the old trial balance showed.
- Why it would have failed
- The new accountant would have signed a return for a year it had never reviewed, on a trial balance with unreconciled intercompany balances.
- The structure adopted
- Model C on a compressed timetable: the outgoing firm delivered the closing file within ten days under a short written protocol, the incoming firm reviewed reconciliations and tax adjustments, corrected two items and filed within the deadline.
- Lesson
- Decide who files the tax return after switching accountants on the day you decide to switch, not in March.
What drives the cost of the tax return after switching accountants?
The cost of the tax return after switching accountants depends on which model is used, how many months the incoming accountant must review, the condition of reconciliations and tax adjustments, the number of related-party transactions, and whether amended returns are needed. Model A costs least in fees and most in risk; Model B costs most in review time.
| Driver | Lower effort | Higher effort |
|---|---|---|
| Model | A or C with cooperation | B without cooperation |
| Books | Monthly reconciliations exist | Year-end balances unsupported |
| Complexity | Single activity, few adjustments | Exemptions, transfer pricing, incentives |
| Corrections | None | Amended returns for several periods |
Turkey vs the United Kingdom
In the United Kingdom, a new accountant is authorised as agent and can file earlier-period returns once engaged; the accountant does not share statutory liability for the tax. In Turkey, the CPA who sends the return is jointly liable for tax loss caused by a mismatch between return and books, which is why Turkish accountants review before they sign.
| Point | Turkey | United Kingdom |
|---|---|---|
| Filing authority | E-return intermediary and liability contract | Agent authorisation |
| Accountant’s statutory liability for the tax | Joint liability within repeated Art. 227 | No general equivalent |
| Consequence for a takeover | Review before signing is standard | Reliance on prior accountant’s work is more common |
The UK column is a general orientation, not advice on UK rules.
Conclusion
Turkish law does not name who files the tax return after switching accountants. It makes the filing CPA responsible for it. Choose a model, write it into the handover protocol and expect the incoming accountant to review the year before signing.
Old-year close and tax return review for takeover clients
Tax Certainty for the year your previous accountant kept.
- Choice of model and handover protocol with the outgoing accountant
- Review of reconciliations, accruals and tax adjustments before signing
- Annual corporate tax return and last e-ledger certificates filed on time
- Amended returns and voluntary disclosure where needed
- Always-on Compliance for the new year
We keep books and file returns as licensed CPAs; legal disputes are handled with your Turkish counsel. Engagements start with a paid scoping consultation, and fees are confirmed in writing.
Request the review by emailRequest a proposal
info@ozmconsultancy.com · +90 216 352 29 61 · WhatsApp +90 506 682 96 55 · Deluxia Palace, Batı Ataşehir, Istanbul
Frequently asked questions on the tax return after switching accountants
Can my new accountant file last year’s corporate tax return in Turkey?
Yes, once the e-return intermediary and liability contract with the new accountant is recorded in the tax office system. Because the signing CPA is responsible for the return matching the books, expect a review of the year before filing.
Is my old accountant still responsible after we terminate?
For the returns that accountant filed, yes. Termination ends the engagement for future periods; it does not remove professional responsibility for returns already signed and submitted.
Does the new accountant become liable for the old accountant’s mistakes?
No, not for returns the old accountant filed. The new accountant becomes responsible for what it signs, including any old-year annual return or amended return that it files.
Who signs the financial statements for the old year?
The financial statements attached to the corporate tax return are signed by the CPA who files the return, together with the company’s authorised signatories. If the company is subject to statutory audit, the auditor’s report is a separate document.
Can two accountants be authorised at the same time during the transition?
The dates of each firm’s filing authority should be planned so that there is no gap. Whether both can hold authority for the same return type at the same time is a system matter to confirm with the tax office portal before the old contract is cancelled.
What if the old accountant will not give us the closing file?
The books and documents belong to the company and must be handed over within 30 days of termination. If they are withheld, see our guide on what to do when a Turkish accountant refuses to hand over books.
Primary sources
- Law No. 3568 on Certified Public Accountancy and Sworn-in Certified Public Accountancy: mevzuat.gov.tr
- Regulation on the Working Procedures and Principles of CPAs and Sworn-in CPAs, Arts. 23, 26 and 27: turmob.org.tr
- Disciplinary Regulation under Law No. 3568 (handover of books within 30 days): TÜRMOB consolidated text
- Regulation on Unfair Competition and the Advertising Ban, Art. 7: Official Gazette of 21 November 2007, No. 26707
- Tax Procedure Law No. 213, Arts. 185–186, 221 and repeated Art. 227; General Communiqué No. 340 (e-return intermediary and liability contract): mevzuat.gov.tr; gib.gov.tr
- Corporate Tax Law No. 5520, Art. 14 (filing period): mevzuat.gov.tr
- Turkish Commercial Code No. 6102, Arts. 64 and 82: mevzuat.gov.tr
- Revenue Administration e-ledger rules: edefter.gov.tr
This article is provided for general informational purposes and does not constitute legal, tax, accounting or investment advice. Professional rules, deadlines and figures are stated as of 11 November 2026 and depend on the specific facts. Professional advice should be obtained before taking action.
Turn Turkey compliance into certainty
SYSTEMS CPA supports foreign-owned companies with company formation, accounting, tax compliance and payroll in Turkey — one accountable local partner. Reviewed by Evren Özmen, SMMM (Certified Public Accountant), TÜRMOB Reg. No. 35675.
