Tax Certainty · Forensic accounting in Turkey · Law No. 6754 · Civil Procedure Code Art. 293
Forensic Accounting Audit in Turkey: Who Can Do It and Will It Hold Up in Court?
A forensic accounting audit in Turkey is a fact-finding examination of books, bank flows and e-documents, built to answer one question for a board, a prosecutor or a judge. Turkey has no separate forensic accountant license, so who signs the report, and under which procedure it is filed, decides how much weight it carries.
Commission a forensic accounting audit before you dismiss anyone, sue anyone or file a criminal complaint in Turkey, and design it for the forum where it will be used. Your own expert establishes the facts and frames the questions; if the dispute reaches court, the judge appoints a court expert (bilirkişi) under Law No. 6754, who may not make legal findings. Several deadlines are preclusive and start early.
- Turkey has no forensic accountant license. The work sits with licensed CPAs under Law No. 3568, registered court experts under Law No. 6754, and Turkish counsel.
- A party expert opinion is lawful supporting evidence (Civil Procedure Code Art. 293; Criminal Procedure Code Art. 67(6)), but no expert report binds the judge (Civil Procedure Code Art. 282).
- An employer has six working days from the moment the person authorized to dismiss learns the facts (Labor Law No. 4857, Art. 26).
- Embezzlement by a private-company employee is prosecuted as qualified breach of trust (Turkish Criminal Code Art. 155(2)); “zimmet” is reserved for public officials.
- Fake invoices found in your own books are a tax problem for the company itself (Tax Procedure Law Art. 359); voluntary disclosure under Art. 371 has strict timing limits.
Key facts at a glance
| Question | Short answer | Basis |
|---|---|---|
| Is there a forensic accountant license in Turkey? | No. Examination, analysis, audit, written opinions, arbitration and expert work fall within a licensed CPA’s statutory scope; court experts must also be registered on regional expert lists. | Law No. 3568, Art. 2; Law No. 6754 |
| Who appoints the expert in a Turkish lawsuit? | The court (or, during an investigation, the prosecutor) when the question needs special or technical knowledge rather than legal knowledge. | Civil Procedure Code (HMK) Art. 266; Criminal Procedure Code (CMK) Art. 63 |
| Can a party file its own forensic report? | Yes, as a party expert opinion (uzman görüşü or bilimsel mütalaa). No extra time can be claimed only for obtaining it. | HMK Art. 293; CMK Art. 67(6) |
| Can a court expert decide who is legally liable? | No. A court expert may not make legal characterizations or evaluations. | Law No. 6754, Art. 3(2) |
| How long does a court expert have to report? | Up to three months, extendable once by up to three months; two plus two months in simple procedure. | HMK Art. 274(1) |
| How long to object to the court expert’s report? | Two weeks from notification, plus one further period of up to two weeks if the response needs technical work. | HMK Art. 281(1) |
| What is the deadline to dismiss a dishonest employee? | Six working days from when the person authorized to dismiss learns the facts, and one year from the act unless the employee obtained a material benefit. | Labor Law No. 4857, Art. 26 |
| Which offense covers employee embezzlement? | Qualified breach of trust: one to seven years’ imprisonment and a judicial fine of up to 3,000 days, prosecuted ex officio. | Turkish Criminal Code (TCK) Art. 155(2) |
| Can minority shareholders force an investigation? | In a joint stock company, yes: a court-appointed special auditor. If the general assembly refuses, holders of 10% of capital (5% if listed) or TRY 1 million nominal value can apply to court within three months. | Turkish Commercial Code (TTK) Arts. 438–439 |
| How far back can records be tested? | Tax records must be kept for five years, counted from the calendar year after the year they relate to; commercial books and records for ten years. | Tax Procedure Law (VUK) Art. 253; TTK Art. 82 |
What is a forensic accounting audit in Turkey?
A forensic accounting audit in Turkey is an evidence-led examination of a company’s ledgers, e-invoices, bank movements, payroll and contracts. It establishes what happened, who benefited and how much was lost, in a form that can support a dismissal, a criminal complaint, a civil claim, a tax correction or an insurance claim. It answers a defined question; it does not issue an audit opinion.
Turkish practice has no single fixed name for this work, and foreign groups often hear four or five terms used loosely. They overlap in technique but differ in who commissions the work, who reads the result and what legal weight it carries.
| Turkish term | What it means | Who commissions it |
|---|---|---|
| Adli muhasebe incelemesi | Forensic accounting examination: the generic term for fact-finding on books and transactions | The company, its parent, counsel or an insurer |
| Uzman görüşü / bilimsel mütalaa | Party expert opinion filed in civil or criminal proceedings | A party to the proceedings (HMK Art. 293; CMK Art. 67(6)) |
| Bilirkişi raporu | Court expert’s report | The court or the public prosecutor (HMK Art. 266; CMK Art. 63) |
| Özel denetim | Special audit of specific events in a joint stock company | The commercial court, after a general assembly request (TTK Arts. 438–440) |
| Vergi incelemesi | Tax examination, typically by the Tax Inspection Board (VDK) | The tax administration (VUK Art. 134 onward) |
| Bağımsız denetim | Statutory independent audit of financial statements; not a fraud investigation | The company, if it meets the thresholds set under TTK Art. 397 |
Forensic accounting audit vs statutory audit: why a clean audit opinion did not catch it
A statutory audit gives reasonable assurance that the financial statements as a whole are free of material misstatement. A forensic accounting audit tests specific transactions, people and money flows down to the document. Under Turkish auditing standard BDS 240, the primary responsibility for preventing and detecting fraud rests with management and those charged with governance, not with the auditor.
That distinction answers the question foreign parents ask most often: “Our Turkish subsidiary had a clean audit report every year, so how did this happen?” A statutory auditor samples, works to materiality and relies partly on management representations. Collusion between an employee and a supplier, or one manager who controls both the purchase order and the payment, can stay below materiality for years. BDS 240, the Turkish adoption of ISA 240 issued by the Public Oversight, Accounting and Auditing Standards Authority (KGK), says this openly.
Internationally, the IAASB’s revised ISA 240 applies to audits of periods beginning on or after 15 December 2026 and sharpens the auditor’s focus on fraud risk. It will not turn a statutory audit into a forensic accounting audit: the purpose, the depth and the output stay different. Ask your auditor which version KGK requires for your reporting period.
| Feature | Statutory audit | Forensic accounting audit | Tax examination (VDK) | Special audit |
|---|---|---|---|---|
| Question | Are the financial statements fairly presented? | What happened, who benefited, how much was lost? | Was the right tax paid? | What are the facts of specific events a shareholder needs? |
| Appointed by | General assembly | Company, parent, counsel or insurer | Tax administration | Commercial court |
| Rules | BDS (Turkish ISAs) | Engagement terms and the evidence rules of the forum | VUK and the tax laws | TTK Arts. 438–444 |
| Depth | Sampling to materiality | Full populations or targeted transactions | Selected taxes and periods | Limited to the events requested |
| Output | Audit opinion | Findings, quantification, exhibits | Examination report and assessments | Special auditor’s report |
| Typical use | Annual reporting | Dismissal, complaint, claim, tax correction, insurance | Assessments, penalties, criminal referral (VUK Art. 367) | Director liability claims |
Is a forensic accounting audit the same as a tax examination?
No. Tax inspectors examine whether tax was correctly paid under the Tax Procedure Law, and their findings can lead to assessments, penalties and a criminal referral for the offenses in VUK Art. 359. A forensic accounting audit is commissioned by the company or its owners to establish facts for their own decisions. The two meet when the forensic work finds fake or misleading invoices: from that moment the findings are also a tax decision, covered under “What happens if” below.
Who can legally do a forensic accounting audit in Turkey?
No Turkish statute creates a “forensic accountant” title. In practice the work belongs to licensed CPAs: Law No. 3568, Art. 2 places examination, analysis, audit, written opinions, reports, arbitration and expert-witness work within a certified public accountant’s statutory scope. A court expert must additionally be registered on the regional expert lists kept under Law No. 6754.
That gives five roles, and most serious cases use at least two of them.
| Role | Legal basis | What they sign | Where it is used |
|---|---|---|---|
| Certified public accountant (SMMM) | Law No. 3568, Art. 2(A) | Examination reports, written opinions, party expert opinions | Internal investigations, HMK Art. 293 and CMK Art. 67(6) opinions, settlement and insurance files |
| Sworn-in CPA (YMM) | Law No. 3568, Arts. 2(B) and 12 | Opinions and reports plus statutory certifications; does not keep books | Where a certification is legally required |
| Court expert (bilirkişi) | Law No. 6754; HMK Art. 266; CMK Art. 63 | Court expert report | Only when appointed by a court or prosecutor |
| Special auditor (özel denetçi) | TTK Arts. 438–444 | Special audit report | Joint stock company disputes, by court appointment |
| Turkish counsel (avukat) | Attorneys Act No. 1136 | Legal opinions, complaints, statements of claim | Legal characterization, strategy and representation |
Can a foreign forensic team work on a Turkish case?
Yes. Data analytics, interviews and reporting to a foreign board can be done by any qualified team, including Certified Fraud Examiners (CFE, a credential of the US-based Association of Certified Fraud Examiners). Three Turkish facts still shape the work. The court will appoint its own registered expert, so a foreign report enters the file only as a party document. The CPA title and regulated accounting work are governed by Law No. 3568. And the books, e-ledgers and court file are in Turkish: a report the court expert cannot read will not move the case.
The model that works is a joint team. The group’s investigators set the questions and the global context, while a Turkish CPA owns the Turkish books, signs any Turkish-language opinion and can be heard at a hearing. That last point matters, because under HMK Art. 293(3) the court does not evaluate a party expert’s report if the expert fails to attend the hearing without a valid excuse.
Having served on the court-appointed side of these files, my advice to foreign groups is simple: write your forensic report for the Turkish court expert who will read it next. A Turkish summary, figures that tie to the statutory books and numbered exhibits are worth more than a polished English slide deck. And choose a signatory who can actually come to the hearing.
Court expert (bilirkişi) vs party expert opinion (uzman görüşü): which report will the judge read?
The judge reads both, but for different purposes. The court expert’s report is evidence the court ordered; a party expert opinion supports one side’s case and helps the court test that report. Neither binds the judge: Civil Procedure Code Art. 282 requires the court to evaluate expert reports freely, together with all the other evidence in the file.
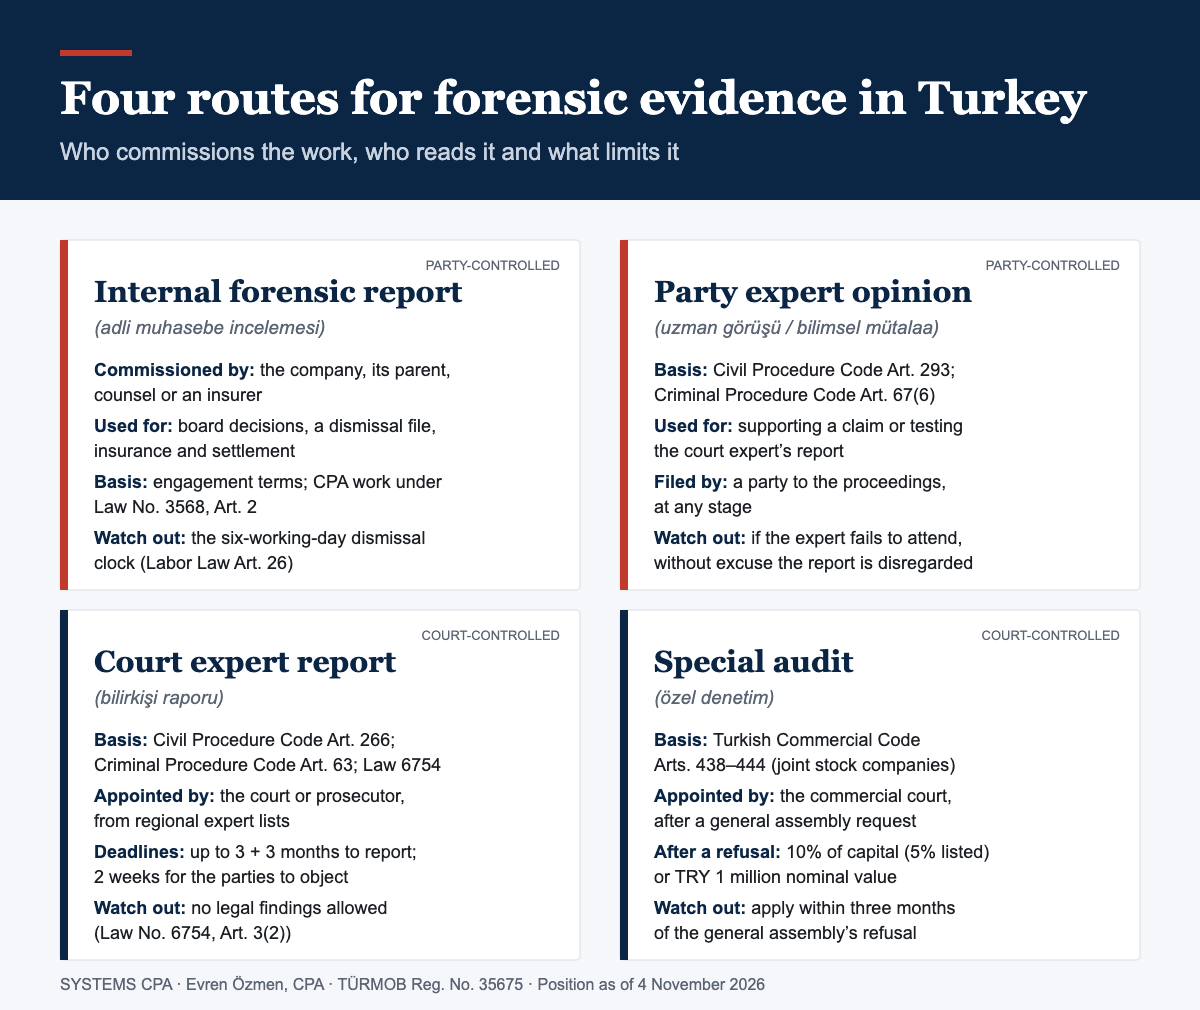
| Feature | Court expert (bilirkişi) | Party expert opinion (uzman görüşü) |
|---|---|---|
| Appointed by | The court or prosecutor, from the regional expert list | The party |
| Legal basis | HMK Arts. 266–287; CMK Arts. 62–73; Law No. 6754 | HMK Art. 293; CMK Art. 67(6) |
| Who pays | Advanced by the parties as court costs and allocated in the judgment (HMK Art. 323) | The party that commissions it |
| Scope limit | Technical facts only; no legal characterization (Law No. 6754, Art. 3(2)) | Technical; legal argument stays with counsel |
| Timing | Deadline set by the court, at most 3 + 3 months (HMK Art. 274) | Any stage; no extra time can be claimed only to obtain it |
| Weight | Evaluated freely by the court (HMK Art. 282) | Evaluated freely; material conflicts with the court expert’s report should be resolved |
| Challenge | Objection within two weeks of notification (HMK Art. 281) | Questions at the hearing; the expert must attend if called (HMK Art. 293) |
What does Law No. 6754 forbid a court expert to do?
Law No. 6754, Art. 3(2) bars a court expert from commenting on anything beyond the matters that require expertise or special or technical knowledge, and from making legal characterizations or evaluations. Art. 3(3) forbids appointing an expert for questions that general knowledge, experience or the judge’s legal knowledge can resolve. In a forensic file, the expert can say that payments to a supplier exceeded documented deliveries by a stated amount; the expert cannot say that the manager committed breach of trust. Regional expert boards discipline experts who cross that line.
How long does a court-appointed expert have?
Under HMK Art. 274(1), the period the court gives its expert cannot exceed three months; at the expert’s reasoned request it can be extended once by up to three months. In cases under simple procedure, both periods are two months. In practice this is the window in which a well-prepared party file, with a clear chronology, reconciled figures and an index of documents, has the most influence, because it shapes the questions before the expert writes.
How do you challenge a court expert’s report you disagree with?
Within two weeks of notification, a party may ask the court to have missing points completed, unclear points explained or a new expert appointed (HMK Art. 281(1)). Where preparing the objection is very difficult or requires special or technical work, the court can grant one further period of up to two weeks, if it is requested within the first two weeks. Attach a party expert opinion that shows, figure by figure, where the report departs from the records. Turkish appellate practice expects trial courts to resolve material contradictions between the two, usually through a supplementary report or a new panel.
When should a foreign parent order a forensic accounting audit of its Turkish subsidiary?
Order a forensic accounting audit when a specific allegation, anomaly or event needs facts that will survive challenge: a whistleblower report, unexplained margin erosion, payments to unfamiliar suppliers, a tax office letter about fake invoices, a shareholder dispute, a pre-acquisition red flag or a senior manager’s sudden exit. The trigger defines the scope; a vague “look at everything” mandate costs more and proves less.
- A whistleblower or anonymous letter naming a person, a supplier or a practice.
- Purchase prices drifting above market, or a new supplier winning volume quickly.
- Cash and bank reconciliations that never quite close, or growing balances in shareholder and staff accounts (Uniform Chart of Accounts 131, 195 and 196).
- A tax office letter, such as a counter-examination record (karşıt inceleme), an invitation to explain (izaha davet, VUK Art. 370) or a VAT refund hold linked to a supplier flagged for fake invoices.
- Joint venture or shareholder deadlock where one side controls the books.
- Acquisition due diligence that reveals revenue quality, cut-off or related-party issues.
- An insurance claim under a fidelity or crime policy that needs a documented loss computation.
If what you need is a broader compliance review rather than an investigation of a specific suspicion, start with a Turkey Entity Health Check. For a target company, see our 2026 due diligence guide to buying a company in Turkey.
The Turkish forensic clock: deadlines that shape a forensic accounting audit
Turkish deadlines start from different events, such as the decision-maker learning the facts, notification of a report or a general assembly vote, and several of them are preclusive: miss them and the right is lost. A forensic accounting audit in Turkey therefore has to be planned backwards from the deadline that matters most for the decision you need to take.
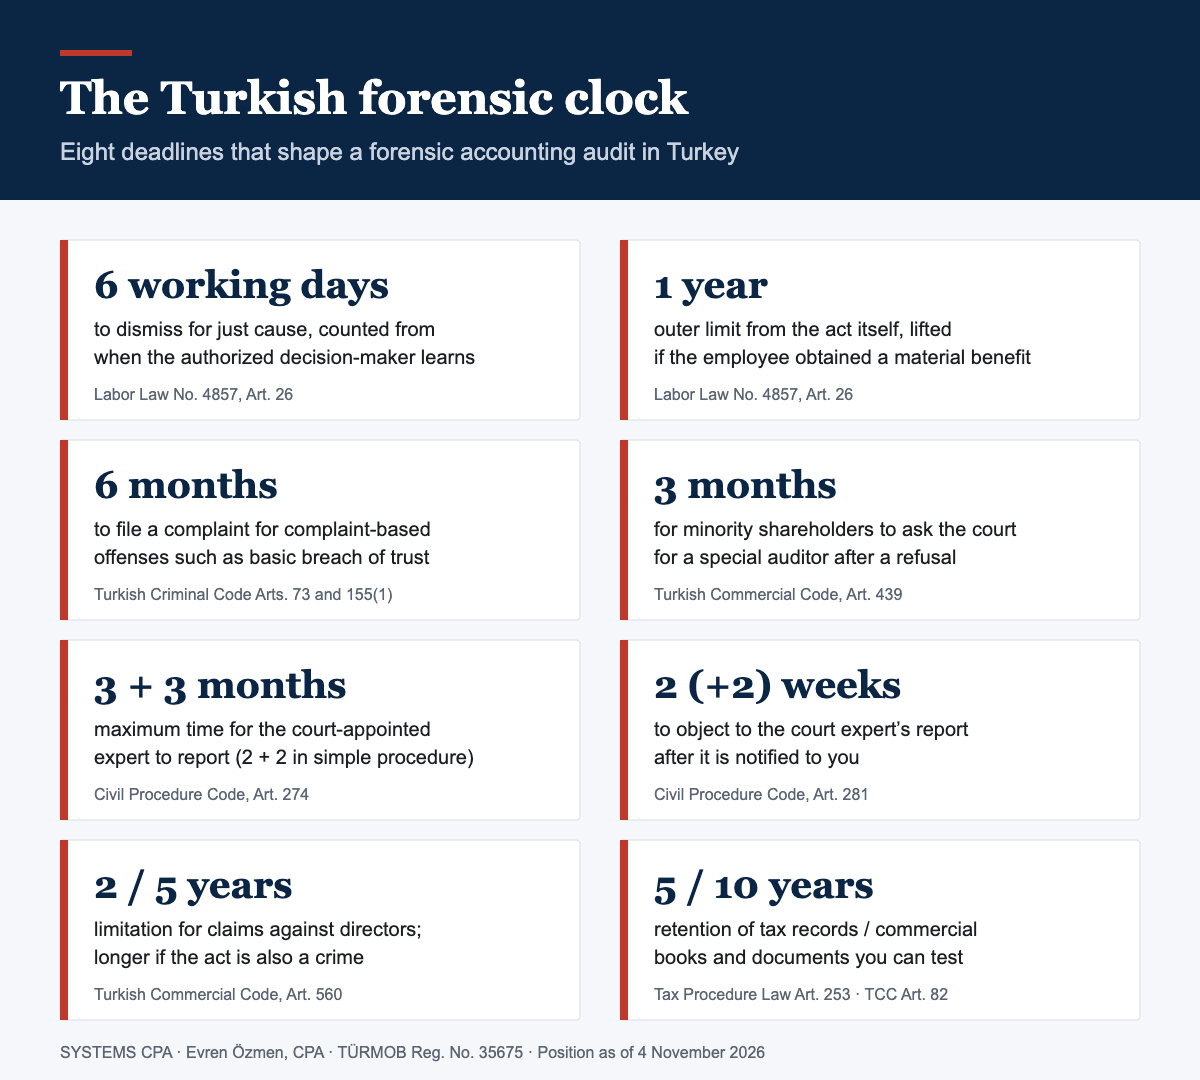
| Deadline | Trigger | What it means for the work | Basis |
|---|---|---|---|
| 6 working days | The person or body authorized to dismiss learns the facts; where an investigation is needed, when its result reaches them | Investigate quickly and keep a dated record of when the decision-maker received the findings | Labor Law Art. 26 |
| 1 year | The act itself | Outer limit for a just-cause dismissal, lifted where the employee obtained a material benefit | Labor Law Art. 26 |
| 6 months | The victim learns the act and the offender | Complaint deadline for complaint-based offenses such as basic breach of trust; qualified breach of trust is prosecuted ex officio | TCK Arts. 73 and 155 |
| 3 months | General assembly rejects a special audit request | Minority shareholders of a joint stock company must apply to the commercial court in time | TTK Art. 439 |
| 3 + 3 months | The court appoints its expert | A party file is most useful before the court expert reports | HMK Art. 274 |
| 2 (+2) weeks | Notification of the court expert’s report | Objections and any party expert opinion must be ready fast | HMK Art. 281 |
| 2 / 5 years | Knowledge of the loss and the responsible person / the act | Limitation for claims against directors; a longer criminal limitation applies if the act is also a crime | TTK Art. 560 |
| 5 / 10 years | The year the records relate to | The window of tax records and commercial books you can demand and test | VUK Art. 253; TTK Art. 82 |
| 5 business days | Signature of a KVKK standard contract | If investigation data goes abroad on a standard contract, the Data Protection Authority must be notified | KVKK Art. 9 |
The six-day rule is where foreign groups most often weaken an otherwise strong case. The local board receives an internal memo in January, waits for headquarters, and dismisses in April. Turkish courts ask when the person or body authorized to dismiss learned the facts, not when the group approved. Decide on day one who that decision-maker is, and date every step.
How a forensic accounting audit works in Turkey: a 7-step process
A Turkish forensic accounting audit moves from evidence preservation to scoping, data acquisition, analysis, interviews, quantification and a report written for its forum. The first two steps decide whether the rest is usable: lost data and a report aimed at the wrong audience are the two failures that cannot be repaired later.
- Preserve evidence before anyone is alerted. Secure ERP and e-mail access, export mailboxes, keep bank portal logs and paper files, and suspend automatic deletion. Altering or destroying data in an information system is a separate offense (TCK Art. 244), and destroying statutory books is a tax smuggling offense (VUK Art. 359(b)), but neither brings the data back. E-invoices and e-ledger berat certificates also exist outside the company’s own systems, which often allows reconstruction.
- Define the question and the forum. Write down the decision the work must support: a dismissal, a criminal complaint, a claim against a director, a tax correction, an insurance claim or a board decision only. Then plan backwards from that forum’s evidence rules and deadlines. Bring in Turkish counsel at this point; legal characterization is counsel’s job, not the accountant’s.
- Acquire the data lawfully. Typical sources are the general ledger and e-ledger, e-invoice and e-archive records, the company’s own bank statements, payroll and social security (SGK) filings, customs declarations, contracts and approval workflows. For periods up to August 2024, monthly Form Ba/Bs filings also show counterparties above TRY 5,000; the forms were abolished from the September 2024 period by VUK General Communiqué No. 565. Third-party bank records are protected by banking secrecy (Banking Law No. 5411, Art. 73).
- Analyze full populations, not samples. Match the supplier master file against employee data such as addresses, IBANs, phone numbers and family names. Test duplicate and split payments, price variances against market, round-sum and weekend postings, credit notes after period end, and movements through shareholder and staff accounts. In a joint stock company, check every transaction between a director and the company: TTK Art. 395 requires general assembly approval.
- Interview and reconcile. Interview process owners first and the person under suspicion last, in a sequence agreed with Turkish employment counsel. Reconcile every finding to a document, a bank movement or an e-invoice before it goes into the report.
- Quantify the loss and its side effects. Compute the direct loss, then the tax effect (VAT deducted on fake invoices, disallowed expenses, penalties), interest and what is realistically recoverable. A loss figure that ignores the tax consequences will be wrong in the court file and in the accounts.
- Report for the forum. An internal report for the board, a dismissal file, an annex to a criminal complaint, a party expert opinion under HMK Art. 293 or CMK Art. 67(6), or a voluntary disclosure file under VUK Art. 371: each needs a different structure, language and level of legal caution.
Two internal disciplines make step four faster next time: a localized ERP with a clean audit trail (see our ERP localization guide for Turkey) and a documented month-end close and financial control routine.
One quantification error recurs in Turkish files: the loss is computed on invoice totals that include VAT the company itself deducted. The court expert will separate the two, and a party report that has not done so loses credibility on page one. Show the net loss, the VAT effect and the penalty exposure in separate columns.
What a forensic accounting audit typically finds in Turkish subsidiaries
Most frauds in Turkish subsidiaries are not sophisticated. They exploit one person controlling two steps of a process: approving a supplier and its payment, booking a credit note and collecting the cash, or preparing payroll and the bank upload. Turkey’s e-document regime makes many of these schemes visible to anyone who examines the full population of transactions.
| Scheme | How it shows up | Usual legal hook |
|---|---|---|
| Fictitious or related supplier | E-invoices with no delivery or service evidence; an address, phone number or IBAN shared with an employee | TCK Art. 155(2); VUK Art. 359 if invoices are fake; TTK Art. 395 for directors |
| Kickbacks on purchasing | One supplier’s prices above market; orders split below approval limits | TCK Art. 155(2); civil claim for damages |
| Ghost or inflated payroll | Names in the payroll file missing from access-control or SGK records; bank files edited after approval | TCK Art. 155(2); social security exposure |
| Sales suppression or skimming | Gaps between POS data, e-archive invoices and cash deposits; unusual credit notes | TCK Art. 155; tax exposure under VUK Art. 359 |
| Fake expense invoices | Invoices from suppliers later flagged by the tax office; payments routed back in cash | VUK Art. 359(b); VAT deduction disallowed |
| Revenue inflation before a sale or bonus date | Cut-off breaks; sales reversed after period end; round trips with related parties | Director liability (TTK Arts. 553 and 560); warranty claims |
| Managers using company funds | Growing shareholder or staff account balances; personal costs booked as business expenses | TCK Art. 155(2); disguised profit distribution risk for related persons (Corporate Tax Law Art. 13) |
What happens if…? Eight situations from Turkish forensic files
What happens if you dismiss the employee before the forensic accounting audit is finished?
You may lose the just-cause defense, or win it narrowly on a thin file. Labor Law No. 4857, Art. 26 gives the employer six working days from the moment the person or body authorized to dismiss learns the facts. Where an investigation is genuinely needed, the Court of Cassation (Yargıtay) starts that period when the result reaches the decision-maker, but an investigation that drags on without reason does not stop the clock. The safe sequence: preserve, investigate quickly, deliver a dated report to the authorized decision-maker, and dismiss within six working days.
What happens if the suspect deletes e-mails or ledger entries?
Deletion is a criminal act in its own right: altering or destroying data in an information system falls under TCK Art. 244, and destroying statutory books or records is a smuggling offense under VUK Art. 359(b). The priority, however, is recovery. E-invoices pass through the Revenue Administration’s systems or licensed integrators, e-ledger berat certificates are uploaded to the Revenue Administration, and banks keep their own records. A forensic image taken on day one remains the best answer to “the data was changed after I left”.
What happens if the forensic accounting audit finds fake invoices in your own books?
The company becomes both victim and taxpayer at risk. Using fake documents is an offense under VUK Art. 359(b), punishable by three to eight years’ imprisonment for acts after 15 April 2022, and VAT deducted on those invoices will be disallowed, with tax-loss penalties tripled under VUK Art. 344(2). Voluntary disclosure (pişmanlık) under VUK Art. 371 avoids the tax-loss penalty only if it is filed before a denunciation or a tax examination begins and, for smuggling acts, before the act is detected; the tax and a surcharge must be paid within 15 days. Decide with counsel within days, not months.
What happens if the court expert’s report contradicts your forensic findings?
Object within two weeks of notification under HMK Art. 281, asking for missing points to be completed, unclear points to be explained or a new expert to be appointed. Attach a party expert opinion under HMK Art. 293 that shows, figure by figure, where the report departs from the records. Turkish appellate practice expects the trial court to resolve a material contradiction between a court expert’s report and a reasoned party expert opinion. Silence after the two weeks is expensive.
What happens if the money went through bank accounts you cannot see?
The company’s own accounts are yours to analyze; third parties’ accounts are not. Banking Law No. 5411, Art. 73 protects customer secrets, which banks may share only with authorities expressly empowered by law, such as a public prosecutor or a court. That is often the practical reason to file a criminal complaint once the internal facts are solid: the prosecutor can obtain the bank records, and the forensic accounting audit can then be updated with them.
What happens if you are a minority shareholder and management refuses access?
Use the statutory information route first. In a limited company, every partner can ask the managers for information on all business and accounts and inspect specific matters (TTK Art. 614), with the court as the fallback. In a joint stock company, shareholders have information and inspection rights (TTK Art. 437) and may then request a special audit of specific events. If the general assembly refuses, holders of 10% of capital (5% if listed) or of shares with a nominal value of TRY 1 million can apply to the commercial court within three months (TTK Art. 439).
What happens if headquarters wants the Turkish e-mails reviewed abroad?
That is a cross-border transfer of personal data under the Personal Data Protection Law No. 6698 (KVKK), Art. 9. Since the amendments in force from 1 June 2024, a transfer needs an adequacy decision, an appropriate safeguard such as a standard contract issued by the Personal Data Protection Board, or one of the limited incidental-transfer exceptions. A signed standard contract must be notified to the Authority within five business days. Many groups therefore review the data in Turkey and export only the findings.
What happens if the CPA finds signs of money laundering?
Independent CPAs are obliged parties under the measures regulation issued under Law No. 5549 on the Prevention of Laundering Proceeds of Crime, so a forensic engagement can trigger a suspicious transaction report to MASAK, Turkey’s financial intelligence unit. Law No. 5549, Art. 4(2) prohibits disclosing that a report was filed, even to the parties to the transaction. A professional engagement letter addresses this at the start, not in the middle of the work.
Send the trigger date and a short summary to info@ozmconsultancy.com. The first question we will ask is which deadline has started and who in your organization is the authorized decision-maker.
Case analyses: three forensic patterns from Turkish practice
These are illustrative composites of fact patterns that recur in Turkish forensic and court-expert work. Names, figures and details are changed; they do not describe any single client.
Case 1 — The purchasing manager, the new supplier and the six-day clock
- Facts
- The Turkish subsidiary (Ltd. Şti.) of a German manufacturer saw packaging costs rise faster than volumes. A supplier registered eighteen months earlier had taken most of the business. An anonymous e-mail to headquarters named the purchasing manager.
- The obvious answer
- Dismiss the manager immediately, file a criminal complaint and let the prosecutor establish the facts.
- Why it would have failed
- There was no evidence beyond the e-mail. An immediate dismissal would have rested on suspicion, and a complaint without documents would have left the reconstruction of the books to a court-appointed expert, slowly and without knowledge of the business.
- The structure adopted
- Evidence was preserved over a weekend. A forensic accounting audit matched the supplier’s e-invoices against goods receipts, prices against three market quotes, and the supplier’s registered address and IBAN against employee records. The findings (overpricing, partial non-delivery and a family link) went in a dated report to the general manager, who held dismissal authority. The dismissal under Labor Law Art. 25(II) followed within six working days, and the complaint under TCK Art. 155(2) went to the prosecutor with the report and exhibits attached.
- The lesson
- Speed matters, but in Turkey the order matters more: evidence, report, authorized decision-maker, dismissal, complaint.
Case 2 — The 50/50 joint venture where one partner kept the books
- Facts
- A Gulf investor held half of a Turkish joint stock company; the local partner ran operations and accounting. Dividends stopped while turnover grew, and trading companies linked to the local partner appeared among the suppliers.
- The obvious answer
- Sue the local directors for damages under TTK Art. 553 straight away.
- Why it would have failed
- Without access to the books, the claim could not be quantified, and the court would have needed its own expert to discover facts the claimant should have pleaded. Limitation was also running: two years from knowledge of the loss and the responsible person (TTK Art. 560).
- The structure adopted
- The investor first exercised its information and inspection rights, then asked the general assembly for a special audit of the related-party transactions. When the request was refused, it applied to the commercial court within three months under TTK Art. 439. In parallel, a forensic accounting audit of the data already available (e-invoices received from the related companies, trade registry records and the dividend history) produced a party expert opinion that framed the special auditor’s questions.
- The lesson
- In Turkey, the statutory access routes are part of the forensic strategy, not a formality before it.
Case 3 — The clean audit report before an acquisition
- Facts
- A European buyer was acquiring a Turkish distributor with audited financial statements and an unqualified opinion. Revenue had jumped in the last quarter before the locked-box date.
- The obvious answer
- Rely on the statutory audit and the seller’s warranties.
- Why it would have failed
- A statutory audit gives reasonable assurance at a materiality level; it is not designed to test every last-quarter sale. Warranty claims after completion are slow and depend on proving what the seller knew.
- The structure adopted
- Targeted forensic procedures before signing: every last-quarter e-invoice was matched to delivery and collection, credit notes issued after the period end were traced, and sales to entities sharing addresses with the seller’s family were isolated. The findings fed a price adjustment and a specific indemnity instead of a general warranty.
- The lesson
- Put forensic procedures where the money is, before signing. See also net debt and debt-like items in Turkish M&A.
What does a forensic accounting audit cost in Turkey? The drivers that set the fee
The cost of a forensic accounting audit in Turkey is set by scope, not by a price list: the question asked, the period and number of entities, transaction volume, the condition of the data, whether the work must withstand court scrutiny, the language of delivery and the urgency created by Turkish deadlines. A narrow, well-defined question is the most effective cost control.
| Driver | Lower effort | Higher effort |
|---|---|---|
| The question | One supplier, one person, one process | “Look at everything” across several years |
| Period and entities | One year, one company | Several years, group companies and related parties |
| Data condition | Complete e-ledger and ERP with an audit trail | Paper archives, manual journals, missing files |
| Forum | Internal board decision | Court-grade party expert opinion with hearing attendance |
| Language | One language | Bilingual report with translated exhibits |
| Third-party evidence | The company’s own accounts | Asset tracing that depends on prosecutor or court requests |
| Urgency | Planned review | Six-working-day or two-week deadlines already running |
Court-appointed expert fees are a separate item: the parties advance them as court costs, and the judgment allocates them (HMK Art. 323). A party expert opinion is paid by the party that commissions it. We confirm our fees in writing after a paid scoping consultation and do not publish price lists.
Turkey vs England & Wales, Germany and the United States: how forensic evidence reaches the judge
Turkey and Germany are court-expert systems: the judge selects the expert, and party reports support or challenge that expert. England and Wales and the United States are party-expert systems: each side instructs its own expert, under court control. A foreign group used to party experts has to adapt its forensic accounting audit to the Turkish model rather than export its home-country playbook.
| Feature | Turkey | England & Wales | Germany | United States |
|---|---|---|---|---|
| Who selects the expert | The court, from regional lists (HMK Art. 266; Law No. 6754) | Usually the parties, with the court’s permission (CPR 35.4); single joint experts are possible (CPR 35.7) | The court (ZPO §404) | The parties |
| Party reports | Allowed as party expert opinions (HMK Art. 293; CMK Art. 67(6)) | The main form of expert evidence | Private reports are treated as party submissions | The main form of expert evidence |
| The expert’s duty | Independent, impartial and objective; no legal characterization (Law No. 6754, Art. 3) | An overriding duty to the court (CPR 35.3) | Impartial assistant to the court | Admissibility gate under Federal Rule of Evidence 702, amended 1 December 2023 |
| What it means for your team | Make the court expert’s job easy and hard to get wrong | Your expert is the witness | Close to the Turkish model | Your expert must survive a Rule 702 challenge |
Arbitration, including arbitration seated in Turkey, usually gives party-appointed experts a larger role. For damages quantification in arbitration, see who prepares a quantum expert report for arbitration in Turkey.
How to choose a forensic accountant in Turkey: eight questions to ask
- Can I verify the license? Ask for the TÜRMOB registration number and check it with the chamber.
- Has the person worked on the court side? Experience as a registered court expert shows how Turkish judges read reports.
- Will the signatory attend a hearing? Under HMK Art. 293(3), the court does not evaluate a party expert’s report if the expert fails to attend without a valid excuse.
- Is the firm independent of the books? Your bookkeeper or statutory auditor has a conflict when their own work is under review.
- Can the team work with Turkish data? Local ERP systems such as Logo, Mikro and Netsis, SAP installations, and e-invoice and e-ledger formats are the raw material.
- Who handles the legal side? A good forensic accountant stays out of legal characterization and works alongside Turkish counsel.
- How is personal data handled? Ask for a KVKK-compliant data protocol, including any cross-border transfer under Art. 9.
- Is the MASAK position explained? An independent CPA is an obliged party under the Law No. 5549 framework; the engagement letter should say how that is handled.
When the findings raise a tax position, such as VAT on fake invoices or the deductibility of a loss, a written Turkish tax opinion closes the loop; see when a foreign company needs one.
Conclusion: what a forensic accounting audit can and cannot do in Turkey
A forensic accounting audit in Turkey cannot replace the court’s own expert, and it should never try to decide guilt. What it can do is establish the facts while the evidence is fresh, keep the employer inside the six-working-day window, quantify the loss together with its tax consequences, and give counsel, prosecutors and court experts a clear and checkable record. Designed for its forum, it is the difference between a case that moves and a case that waits for a stranger to rebuild your books.
Forensic Accounting Audit for Turkish entities
Peace of Mind and Tax Certainty when the numbers in your Turkish entity stop adding up. A CPA-led forensic accounting audit designed for the forum where it will be used: your board, a labor court, a public prosecutor, a commercial court or the tax office.
- Evidence-preservation and scoping memo mapped to the Turkish deadlines
- Data acquisition from e-ledger, e-invoice, bank, payroll and SGK records under a KVKK-compliant protocol
- Bilingual (Turkish and English) findings report with traceable, numbered exhibits
- Party expert opinion under HMK Art. 293 or CMK Art. 67(6), with hearing attendance
- Support for objections to court expert reports within the HMK Art. 281 window
- Tax consequences quantified: VAT, disallowed expenses and voluntary disclosure options
We do not make legal characterizations, represent clients in court or act as your statutory auditor; we work alongside your Turkish counsel. Engagements start with a paid scoping consultation, and fees are confirmed in writing.
Request the review by emailRequest a proposal
info@ozmconsultancy.com · +90 216 352 29 61 · WhatsApp +90 506 682 96 55 · Deluxia Palace, Batı Ataşehir, Istanbul
Forensic accounting audit in Turkey: frequently asked questions
Is a forensic accounting audit report admissible in a Turkish court?
Yes, as documentary evidence or as a party expert opinion under HMK Art. 293 in civil cases and CMK Art. 67(6) in criminal cases. It does not replace the court-appointed expert, and the judge evaluates all expert evidence freely under HMK Art. 282. A report carries more weight when it is in Turkish, ties to the statutory books and its signatory can be heard at the hearing.
Who can perform a forensic accounting audit in Turkey?
There is no separate forensic accountant license. Licensed CPAs and sworn-in CPAs perform the accounting examination under Law No. 3568, Art. 2; court experts must also be registered under Law No. 6754; Turkish counsel handles legal characterization. Foreign investigators can take part, but Turkish-language, court-facing work should be signed by a professional who can appear before a Turkish court.
How long does a forensic accounting audit take in Turkey?
There is no statutory duration for a private engagement; it depends on the question, the period, the volume and the condition of the data. A narrow question about one supplier or one person is usually measured in weeks, a multi-year reconstruction across several entities and bank accounts in months. A court-appointed expert gets up to three months, extendable once by three months (HMK Art. 274).
What is the difference between a forensic accounting audit and a statutory audit?
A statutory audit gives reasonable assurance that financial statements are free of material misstatement, using sampling and materiality. A forensic accounting audit tests specific transactions and people to establish facts and quantify a loss for a decision or a dispute. Under BDS 240, preventing and detecting fraud is primarily the responsibility of management and those charged with governance, not of the statutory auditor.
Can I dismiss an employee in Turkey based on a forensic report?
Yes, if the report establishes conduct that breaches the duty of loyalty under Labor Law No. 4857, Art. 25(II), and you act within six working days of the authorized decision-maker learning the facts and within one year of the act. The one-year limit does not apply where the employee obtained a material benefit. Take Turkish employment-law advice on the sequence before acting.
Is employee embezzlement in Turkey prosecuted as “zimmet”?
Not for private-sector employees. Zimmet under TCK Art. 247 applies to public officials. A private-company employee who misappropriates money or goods entrusted because of the job commits qualified breach of trust under TCK Art. 155(2), punishable by one to seven years’ imprisonment and a judicial fine of up to 3,000 days, and prosecuted ex officio.
Can a foreign parent order a forensic audit of its Turkish subsidiary?
Yes. As shareholder, and usually through the subsidiary’s own board or managers, the parent can commission a forensic accounting audit of the subsidiary’s books and processes. Personal data must be processed in line with KVKK, and moving employee data abroad needs an Art. 9 mechanism, such as a standard contract notified to the Personal Data Protection Authority within five business days.
How much does a forensic accounting audit cost in Turkey?
Fees depend on scope: the question, the period and entities, the condition of the data, the forum (internal or court-grade), the language and the urgency. Court-appointed expert fees are separate court costs allocated in the judgment (HMK Art. 323). A tightly defined question is the most effective way to control cost. We confirm fees in writing after a paid scoping consultation.
Can minority shareholders demand a forensic investigation of a Turkish company?
In a joint stock company, shareholders who have used their information rights can ask the general assembly for a special audit of specific events (TTK Art. 438). If it refuses, holders of 10% of capital (5% if listed) or of shares with a nominal value of TRY 1 million can apply to the commercial court within three months (TTK Art. 439). Limited company partners have broad information and inspection rights under TTK Art. 614.
What records can a forensic accountant access in Turkey?
The company’s own records: the general ledger and e-ledger, e-invoices and e-archive invoices, statements for its own bank accounts, payroll and SGK filings, customs files and contracts. Tax records are kept for five years (VUK Art. 253) and commercial books for ten (TTK Art. 82). Third parties’ bank records are protected by banking secrecy (Banking Law Art. 73) and generally reach the file only through a prosecutor or court.
Does uncovering fraud create a tax problem for the company?
Often, yes. If fake or misleading invoices are in the books, VAT deductions are disallowed and tax-loss penalties apply, tripled for VUK Art. 359 acts under VUK Art. 344(2). Voluntary disclosure under VUK Art. 371 is available only before a denunciation or tax examination and, for smuggling acts, before the act is detected, with the tax and surcharge paid within 15 days.
Primary sources
- Law No. 6754 on Experts (Bilirkişilik Kanunu), in particular Art. 3: mevzuat.gov.tr; publication in the Official Gazette of 24 November 2016, No. 29898
- Civil Procedure Code No. 6100 (HMK), Arts. 266–287, 293 and 323: mevzuat.gov.tr
- Criminal Procedure Code No. 5271 (CMK), Arts. 62–73: mevzuat.gov.tr
- Turkish Commercial Code No. 6102 (TTK), Arts. 82, 395, 397, 437–444, 553, 560 and 614: mevzuat.gov.tr
- Turkish Criminal Code No. 5237 (TCK), Arts. 73, 155, 244 and 247: mevzuat.gov.tr
- Tax Procedure Law No. 213 (VUK), Arts. 134, 253, 344, 359, 367, 370 and 371: mevzuat.gov.tr
- VUK General Communiqué No. 565 ending Form Ba/Bs from the September 2024 period: Turkish Revenue Administration (gib.gov.tr); Official Gazette of 25 September 2024, No. 32673
- Labor Law No. 4857, Arts. 25 and 26: mevzuat.gov.tr
- Law No. 3568 on Certified Public Accountants and Sworn-in CPAs, Arts. 2 and 12: mevzuat.gov.tr
- Personal Data Protection Law No. 6698 (KVKK), Art. 9: mevzuat.gov.tr; KVKK notice on standard contract notifications
- Law No. 5549 on the Prevention of Laundering Proceeds of Crime, Art. 4: mevzuat.gov.tr
- Banking Law No. 5411, Art. 73: mevzuat.gov.tr
- Corporate Tax Law No. 5520, Art. 13: mevzuat.gov.tr
- KGK, BDS 240 on the auditor’s responsibilities relating to fraud: kgk.gov.tr
- IAASB, ISA 240 (Revised): iaasb.org
- Comparative rules: Civil Procedure Rules Part 35 (England & Wales); Federal Rule of Evidence 702 (United States); ZPO §404 (Germany)
Disclaimer. This article is provided for general information and does not constitute legal, tax, accounting or investment advice. The treatment of a Turkish case depends on the company’s structure, the forum, the evidence and the specific facts, and deadlines run from different trigger dates, some of them preclusive. Advice from Turkish counsel and a licensed CPA should be obtained before acting.
Turn Turkey compliance into certainty
SYSTEMS CPA supports foreign-owned companies with company formation, accounting, tax compliance and payroll in Turkey — one accountable local partner. Reviewed by Evren Özmen, SMMM (Certified Public Accountant), TÜRMOB Reg. No. 35675.
